Greater Lansing Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

Oct. 2, 2026

Why So Many Sellers Are Cutting Their Price Right Now

Seeing a price reduction on a home can raise questions.

Sellers may worry it means they’re losing money. Buyers may wonder if something is wrong with the property.

But with price cuts becoming increasingly common, there’s usually a simpler explanation: the market has changed, and sellers are adjusting.

More Than 4 in 10 Listings Have Had a Price Cut

According to HousingWire Data, the share of sellers reducing their asking price has increased for seven consecutive months.

Today, about 42% of active listings have had at least one price reduction, with the typical reduction around $17,560.

Why?

Buyers are dealing with higher borrowing costs while also having more homes to choose from. That gives them more time to compare properties and be selective about price.

Homes that start too high may have a harder time attracting attention, which can eventually lead sellers to adjust.

For sellers, this makes getting the price right from the beginning especially important.

For buyers, a price reduction doesn’t automatically mean there’s something wrong with the home. It may simply mean the seller is responding to current market conditions.

Sellers Are Adjusting Their Expectations

National list prices have also moved lower from last year’s peak.

Some of that is seasonal, since asking prices typically soften during certain parts of the year. But it also reflects sellers becoming more realistic about what today’s buyers can afford.

With mortgage rates affecting buying power, there’s a limit to how far many buyers can stretch.

Sellers who recognize that early may have a better chance of attracting serious buyers instead of making multiple price reductions later.

Buyers Have More Negotiating Room

There’s another major shift happening.

Redfin data shows there are significantly more sellers than buyers nationally. That means buyers have more choices and, in many markets, more negotiating power than they’ve had in recent years.

That can create opportunities to negotiate more than just the purchase price.

Depending on the property and local market, buyers may be able to ask for help with closing costs, repairs, timing, or other concessions.

For sellers, it means your home needs to compete on more than price alone. Condition, presentation, marketing, and flexibility can all influence which home a buyer chooses.

Bottom Line

Price reductions aren’t automatically a sign that something is wrong with a home or the housing market.

Often, they’re simply the market finding the price buyers are willing and able to pay.

Whether you’re buying or selling, knowing what homes are actually selling for in your specific neighborhood matters far more than the original asking price.

Let’s look at the numbers in your local market so you can make your next move with better information.
Posted in Market Updates
Oct. 2, 2026

What Higher Mortgage Rates Mean for Home Sellers

Higher mortgage rates don’t only affect buyers. They can also change what it takes to successfully sell your home.

When rates rise, buyers become more focused on their monthly payment and overall affordability. That means sellers aren’t just competing with other homes on price, location, and condition anymore. In some markets, they’re also competing with incentives offered by homebuilders.

Builders Are Using Incentives To Attract Buyers

New construction has an advantage that many sellers may not immediately think about: builders can offer incentives designed to make the monthly payment more affordable.

According to Realtor.com, nearly 1 in 5 newly built homes advertise some type of buyer incentive.

One of the most common is a reduced mortgage rate, often offered through a rate buydown. The builder contributes money upfront to help the buyer secure a lower rate, which can reduce the buyer’s monthly mortgage payment.

Other incentives can include closing cost assistance, upgrades, or price adjustments.

For buyers comparing several homes, those savings can make new construction especially appealing.

Existing Home Sellers Have Options Too

Builders aren’t the only ones who can offer incentives.

Depending on the buyer’s loan and the terms of the transaction, a seller may be able to contribute toward a mortgage rate buydown or help with closing costs.

But that doesn’t mean every seller needs to offer an incentive.

Sometimes the better strategy is adjusting the price. In other situations, making certain repairs, offering a concession, or emphasizing features and location advantages that a new development can’t offer may have a greater impact.

The right approach depends on your home, your competition, and what buyers in your local market value most.

Pricing Matters Even More

Today’s buyers are looking closely at the total cost of owning a home.

That means pricing based on what similar homes sold for a few years ago may not reflect what buyers can comfortably afford today.

At the same time, sellers don’t automatically need to make a major price reduction simply because mortgage rates are higher.

The key is understanding what buyers are comparing your home against, including nearby resale homes and new construction, and positioning your property accordingly.

Bottom Line

Higher mortgage rates are making buyers more selective about where their money goes.

For sellers, that makes the right combination of pricing, presentation, marketing, and potentially incentives more important.

If you’re considering selling, let’s look at what buyers are seeing in your local market and determine how to position your home to compete.

Posted in Market Updates
Oct. 2, 2026

The Mortgage Rate You See Online May Not Be the Rate You Actually Get

Mortgage rates are making headlines again, and seeing those numbers online can make buying a home feel more expensive than expected.

But there’s something important to know:

The mortgage rate you see online isn’t necessarily the rate you’ll qualify for.

The rate you’re offered depends on your individual financial situation, the loan you choose, and even how your purchase is structured.

What Determines Your Mortgage Rate?

There isn’t one mortgage rate that applies to every buyer. A lender will look at several factors when determining yours, including:

Your credit score: Generally, a stronger credit profile can help you qualify for more favorable loan terms.

Your debt to income ratio: Lenders compare your monthly debt payments with your income to understand how much additional debt you may comfortably handle.

Your down payment: How much you put down affects your loan to value ratio and can influence your financing options.

Your loan type and term: Conventional, FHA, VA, adjustable rate, and other loan programs can come with different rates and requirements.

There may also be ways to improve the overall cost of your financing.

For example, a mortgage rate buydown could lower your rate in exchange for an upfront cost. In some transactions, the seller or builder may contribute toward that cost.

Seller concessions may also help cover certain closing costs, potentially leaving you with more cash available for your down payment or other expenses.

Start With Preapproval

Instead of trying to determine what you can afford based on the mortgage rates you see online, talk with a lender about your specific situation.

A prequalification can give you a general estimate based largely on the information you provide.

A preapproval goes further. The lender verifies your financial information and gives you a clearer picture of how much you may be able to borrow and what your financing could look like.

That information can make a big difference when deciding whether it makes sense to buy now or wait.

Questions Worth Asking Your Lender

When you speak with a lender, ask how your options could change if you waited three, six, or twelve months.

You can also ask what steps could help improve your financing, whether a different loan program makes sense, and how changes in mortgage rates could affect your monthly payment and buying power.

The goal isn’t to rush into buying. It’s to know your actual numbers before making the decision.

Bottom Line

The mortgage rate making headlines is a market benchmark, not necessarily your personal mortgage rate.

Your credit, debt, down payment, loan program, and other factors all play a role in what you may actually qualify for.

Before letting an online rate convince you that buying is out of reach, talk with a trusted lender and find out what the numbers look like for you.

Posted in Market Updates
Oct. 2, 2026

Hoping for a Housing Crash? Here’s What Experts Are Actually Saying

Some buyers are worried home prices are headed for a crash. Others are hoping for one, especially if lower prices could make buying a home more affordable.
But what are housing experts actually expecting?

Fannie Mae recently surveyed more than 100 housing experts about where home prices could be headed. Their latest forecast points to continued price growth through 2030.

Even the more pessimistic experts aren’t forecasting a crash.

Home Prices Are Still Expected To Rise

On average, the panel expects home prices to increase about 14.7% over the next five years.

Even among the more pessimistic forecasts, prices are still projected to rise about 6.6% by the end of 2030.

That doesn’t mean every market will move the same way. Real estate is local, and some areas may see stronger growth while others could experience flatter prices or short term declines.

But nationally, the experts surveyed are still expecting prices to move higher over time.

Growth May Be Slower, But It’s Still Growth

The forecast has changed slightly compared with a year ago.

Experts now expect prices to grow about 2.5% this year, up from their previous forecast of 2.1%.

For 2027 through 2029, expectations have cooled somewhat. But the important distinction is that slower appreciation isn’t the same thing as falling home prices.

Instead, it could signal a housing market returning to a more normal pace after several unusual years.

What Could That Mean for Homeowners?

Consider a $400,000 home purchased at the beginning of the year.

Based on the panel’s latest forecast, that home could gain roughly $58,000 in value over the next five years from price appreciation alone.

Of course, forecasts aren’t guarantees, and your results will depend heavily on your local market.

But for buyers waiting specifically for a major housing crash before making a move, current expert forecasts don’t point in that direction.

Bottom Line

Home price growth may slow, and some local markets may perform differently than others. But nationally, experts are still forecasting higher home prices through 2030.

If you’re wondering what this could mean for home values in your area, let’s look at what’s happening in the local market and how it fits with your plans.

Posted in Market Updates
Aug. 24, 2026

One Number Could Change Everything About Your Next Move


When's the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor's house sold for. What yours is actually worth right now.

For a lot of homeowners, it's been years. And if you've been thinking about moving, but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number.

Your House May Be Worth More Than You Think

Home values have climbed significantly over the past 5-10 years. And even though today's market is more balanced, homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast.

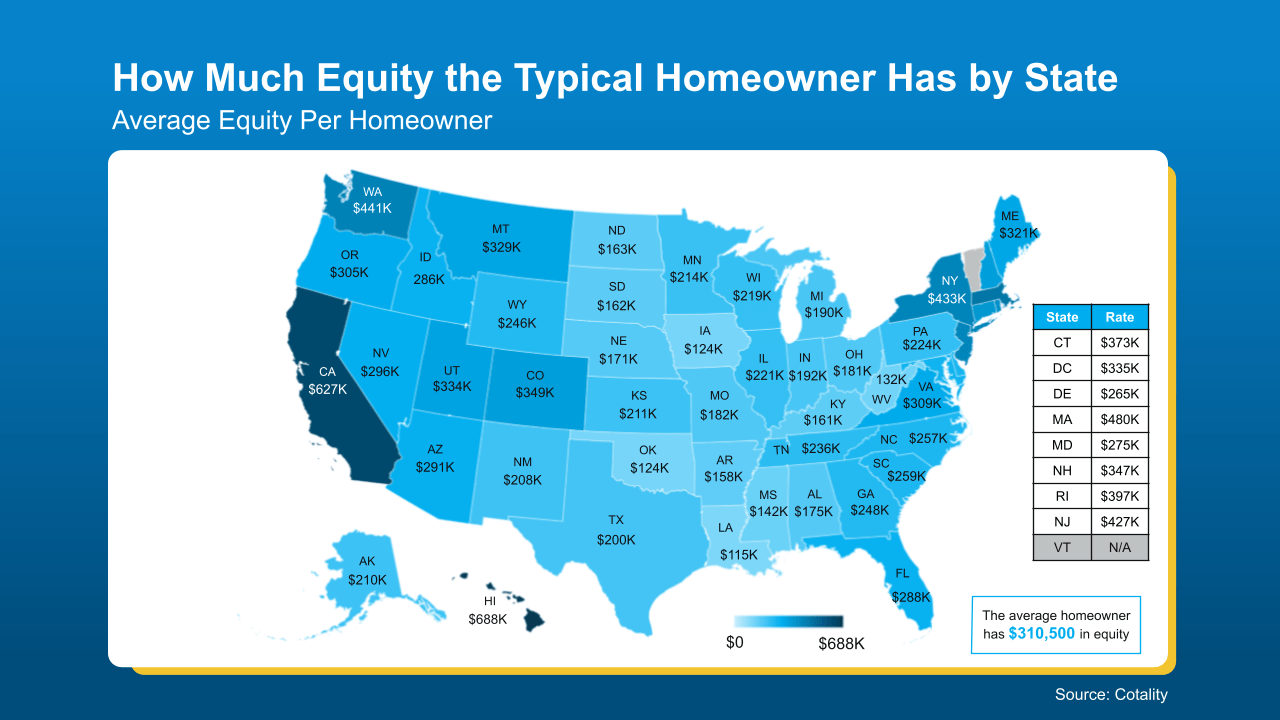
According to Cotality, the typical homeowner with a mortgage now has $310,500 in equity. That's not a small number. It’s six figures.

And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below):

a map of the united statesEven though every local market is different, the question you should be asking right now is the same: How much equity have you built up?
Because if you don’t know that number, you’re missing out.

This Could Be the Missing Piece in Your Move

Most people assume that because prices are higher and rates aren't at 3% anymore, moving just isn't realistic right now, especially if they already have an ultra-low rate. And that's understandable – those are real factors.

But they're not the only factors.

When you have that much equity in your house, you're not starting from scratch. You're not scraping together a down payment or hoping the numbers work. You're walking into your next move with more of an advantage than you think. And that changes the math. 

What Your Equity Can Do for You

Maybe you've outgrown your current house or you're ready to downsize… The equity you've built could help bridge the gap between where you are today and where you want to be next.

Yes, your next house may cost more than your last one did. But your equity could cover a big chunk of that difference. Depending on how much you've built, it could help you:

  • Lower your monthly payment on your next home. The bigger your down payment on your next place, the less you have to borrow. And with today's rates, borrowing less can make a big difference in what you pay every month. 

  • Buy your next house with all cash. This surprises a lot of people, but some homeowners have built enough equity to buy their next home outright, in cash. According to the National Association of Realtors, more than one-quarter (26%) of repeat buyers paid all cash for their home in July. 

  • Transform the home you already have. Love your neighborhood but not your floor plan? You don’t have to move. Your equity could help fund renovations that make your home fit your life today while potentially adding value for tomorrow.

Your equity doesn't erase the challenges of the current market. But it does mean you're walking into your next move with a lot more power and flexibility than you think.

That’s why the value of your home isn't something you should have to wonder about. 

If you're even thinking about a move – or if you're just curious what your options might be – the smartest thing you can do is get a Professional Equity Assessment. It’ll give you a real, market-based evaluation of what your house is really worth right now and how much equity you’re working with.

Because once you see the number, maybe it’s not about whether you can afford to move – it's about what kind of move makes sense for you.

Bottom Line

If it's been a while since you've gotten a professional look at your home's value, let's change that. 

Reach out for a free, personalized Home Equity Assessment that estimates what your house could sell for, how much equity you've likely built, and what that could mean for your next move.


Posted in Market Updates
Aug. 24, 2026

Most Home Sales Close – Here’s How To Keep Yours on Track


Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table.

According to the latest data from Redfin, only about 1 in 7 pending sales are falling through. Meaning the vast majority make it all the way to closing.

And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market.

Why Some Deals Fall Apart Before Closing

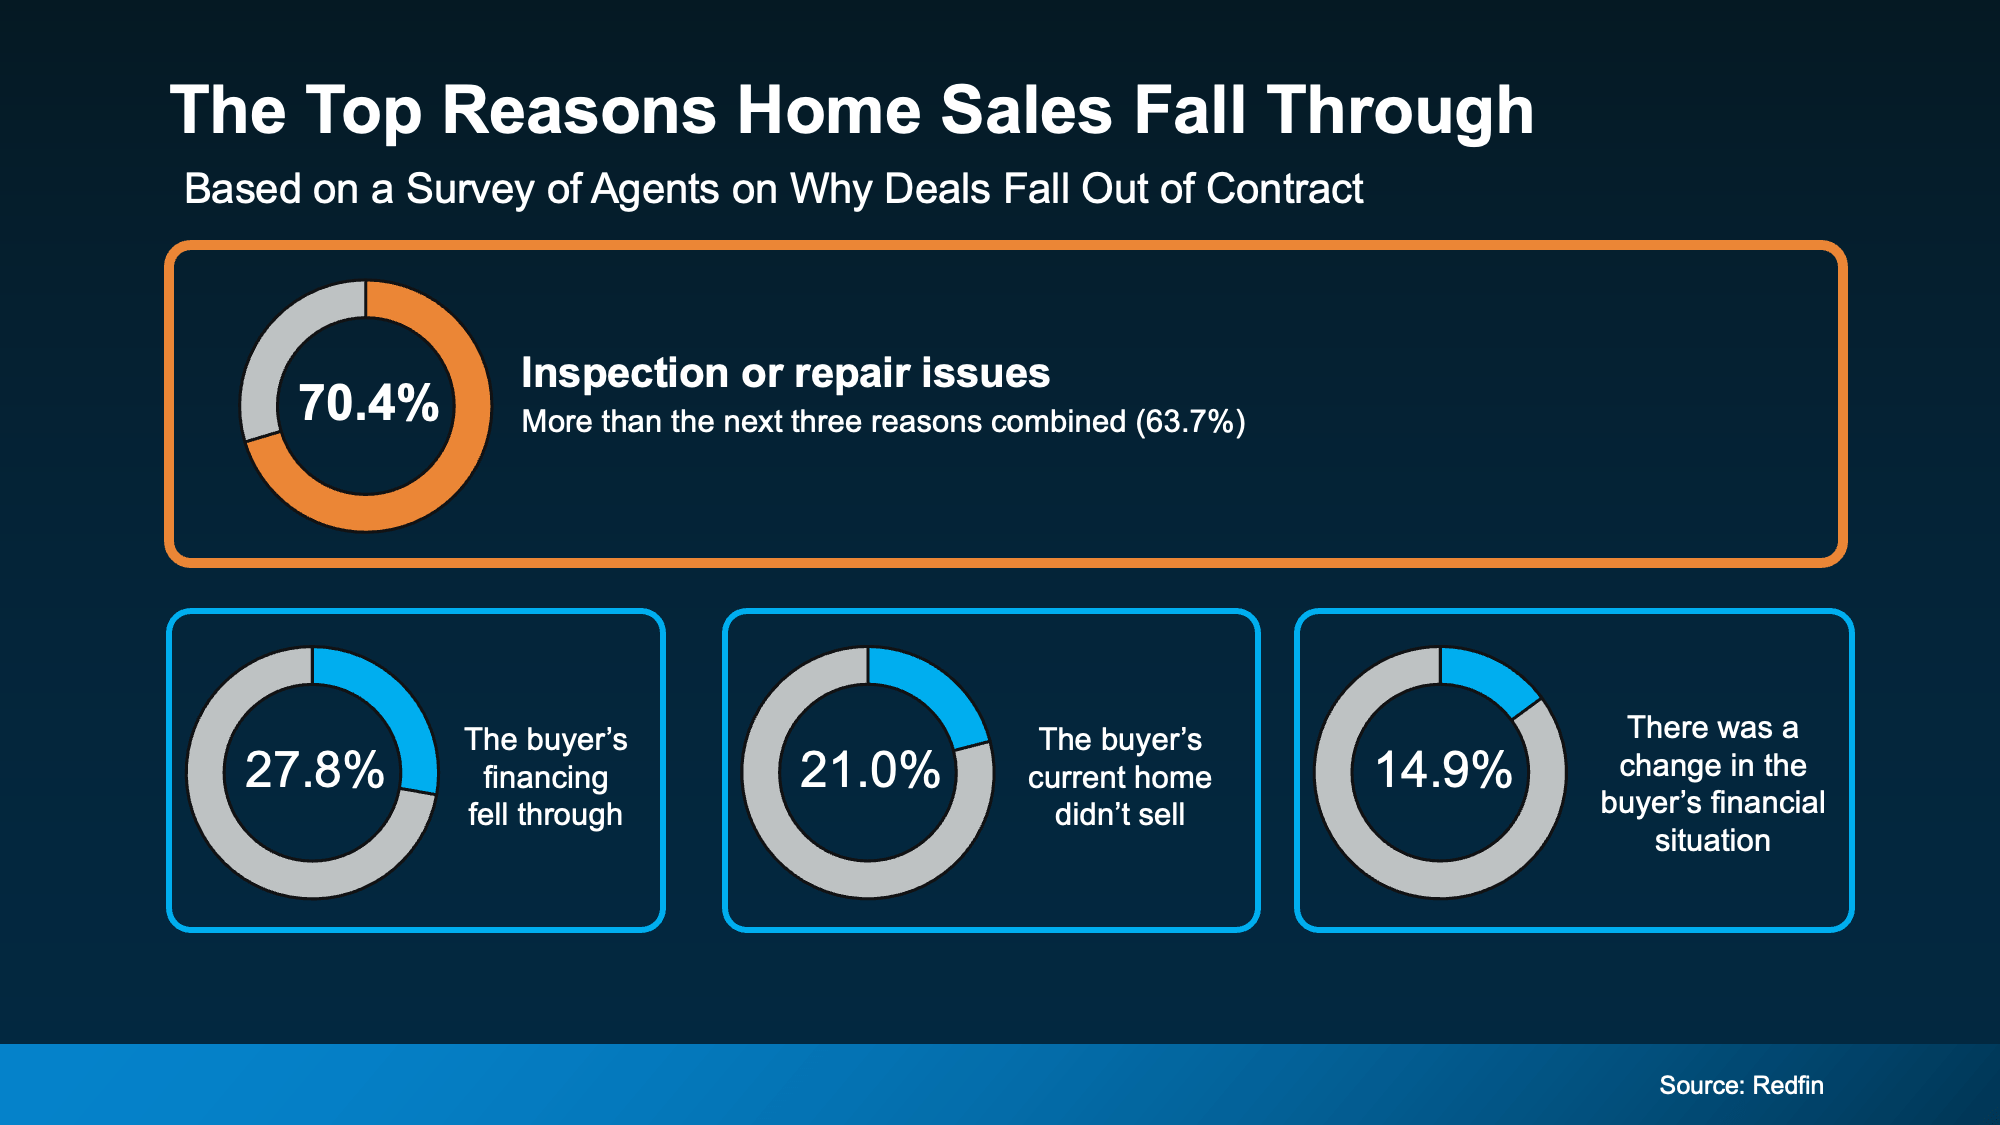
A Redfin survey sheds light on the most common things that trip up a sale (see visual below):

a blue and orange chart with text

Here’s a bit more information on each one.

  • Inspection or repair issues. This is the big one. When a buyer’s inspector finds a problem, whether with the roof, the plumbing, the foundation, or elsewhere, the buyer can push back, ask you to make repairs, request a credit so they can do it themselves, or see if you’ll lower your price. If they don’t get what they want, they may walk away from the deal altogether.

  • The buyer’s financing fell through. Their mortgage loan has to be fully approved in time for closing day. If the loan doesn’t come together, the sale can’t move forward. 

  • The buyer’s current house didn’t sell. Some buyers need to sell their own home before they can close on yours. If that takes longer than expected, you may run into some issues with your timeline or even see them give up on their move.

  • There was a change in buyer’s financial situation. A new job, a big purchase, or new debt can change what a buyer qualifies for on their mortgage loan, even after they were pre-approved.

Where Your Agent Makes the Difference

Some of those reasons are outside your control, like whether a buyer’s loan clears or whether they sell their own home in time. But according to Zillow, there are a few proactive things you can do to help make sure your sale goes as smoothly as possible:

  • Save yourself the headache and get a pre-listing inspection. That’s when you get your own inspection before a buyer gets theirs. It lets you find the big issues before a buyer’s inspector does, so you can fix them or disclose them on your terms, instead of scrambling once you're under contract. In this situation, your agent will help you decide what's worth addressing and what to just disclose. Handle it now, and the biggest risk to your sale is behind you before a buyer ever brings it up.

  • Look at more than just the offer price. Your agent will help you weigh the whole offer, including the buyer’s timeline and any contingencies attached. When a buyer’s offer depends on selling their own home first, the success of your sale rides on a second deal you can’t see. Sometimes, a slightly lower offer with fewer strings is the safer one. Your agent will help you weigh your options and make a plan that works well for you. 

One of those is something you can’t do until you have offers in hand, but the other is something you can get ahead of right now. The pre-listing inspection.

That relatively small cost upfront can save you the much bigger hassle of a deal falling apart later. And while getting your own inspection before listing may not make sense in every market, your agent can tell you whether it’s worth it based on your market, your house, and what buyers are prioritizing in your area.

Sometimes the smartest move is staying one step ahead.

Bottom Line

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish. So, let’s connect and get your house sold. 

Posted in Market Updates
Aug. 24, 2026

Who Has the Upper Hand in Today's Housing Market?


Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know if they'll still get top dollar.

The interesting thing is... both can be right at the exact same time. It just depends on where you live.

That's because today's housing market isn't moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle.

And knowing which market you're actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down.

One Number Tells You Who's Got Leverage

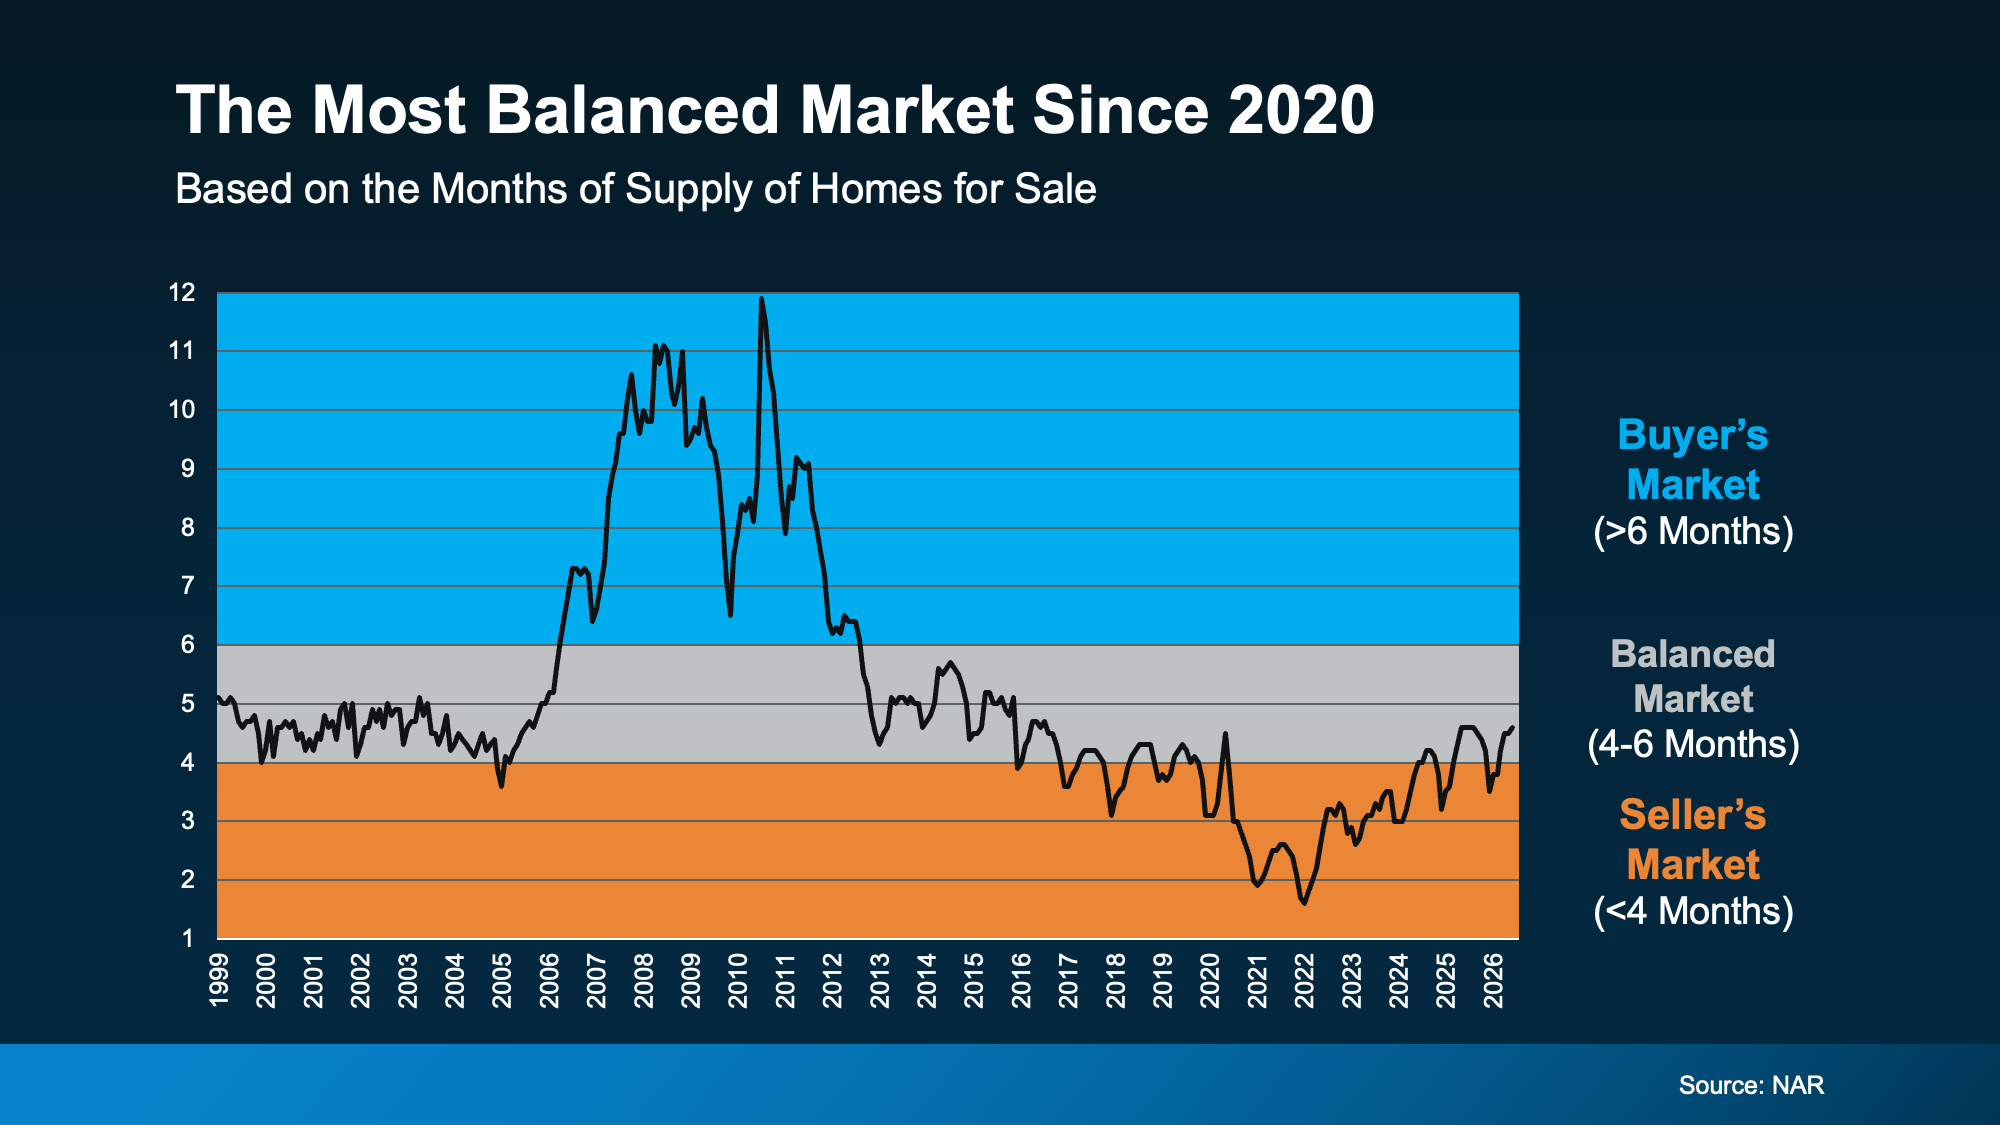
So how do you know which market you're in? There's one number that tells the story faster than anything else: the months' supply of homes for sale. It's the clearest signal of who's got leverage – and what strategy you'll need. Think of it like this.

Imagine no additional homes were listed starting today. Months' supply tells us how long it would take to sell everything that's currently on the market based on today’s demand. 

Generally speaking, if months’ supply is:

  • Fewer than 4 months: Sellers usually have the advantage.

  • 4 to 6 months: Buyers and sellers are on more equal footing.

  • More than 6 months: Buyers can usually negotiate for a better deal.

Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):

a graph of a market

That means, as a whole, the market has finally moved back into a much more balanced range after years of being tilted in sellers’ favor. While that may look like the scales have tipped only slightly, it’s enough to make a real difference in what strategy you’ll need for your move – at least in most places.

The Tale of Two Markets: Why 'Balanced' Doesn't Mean the Same Thing Everywhere

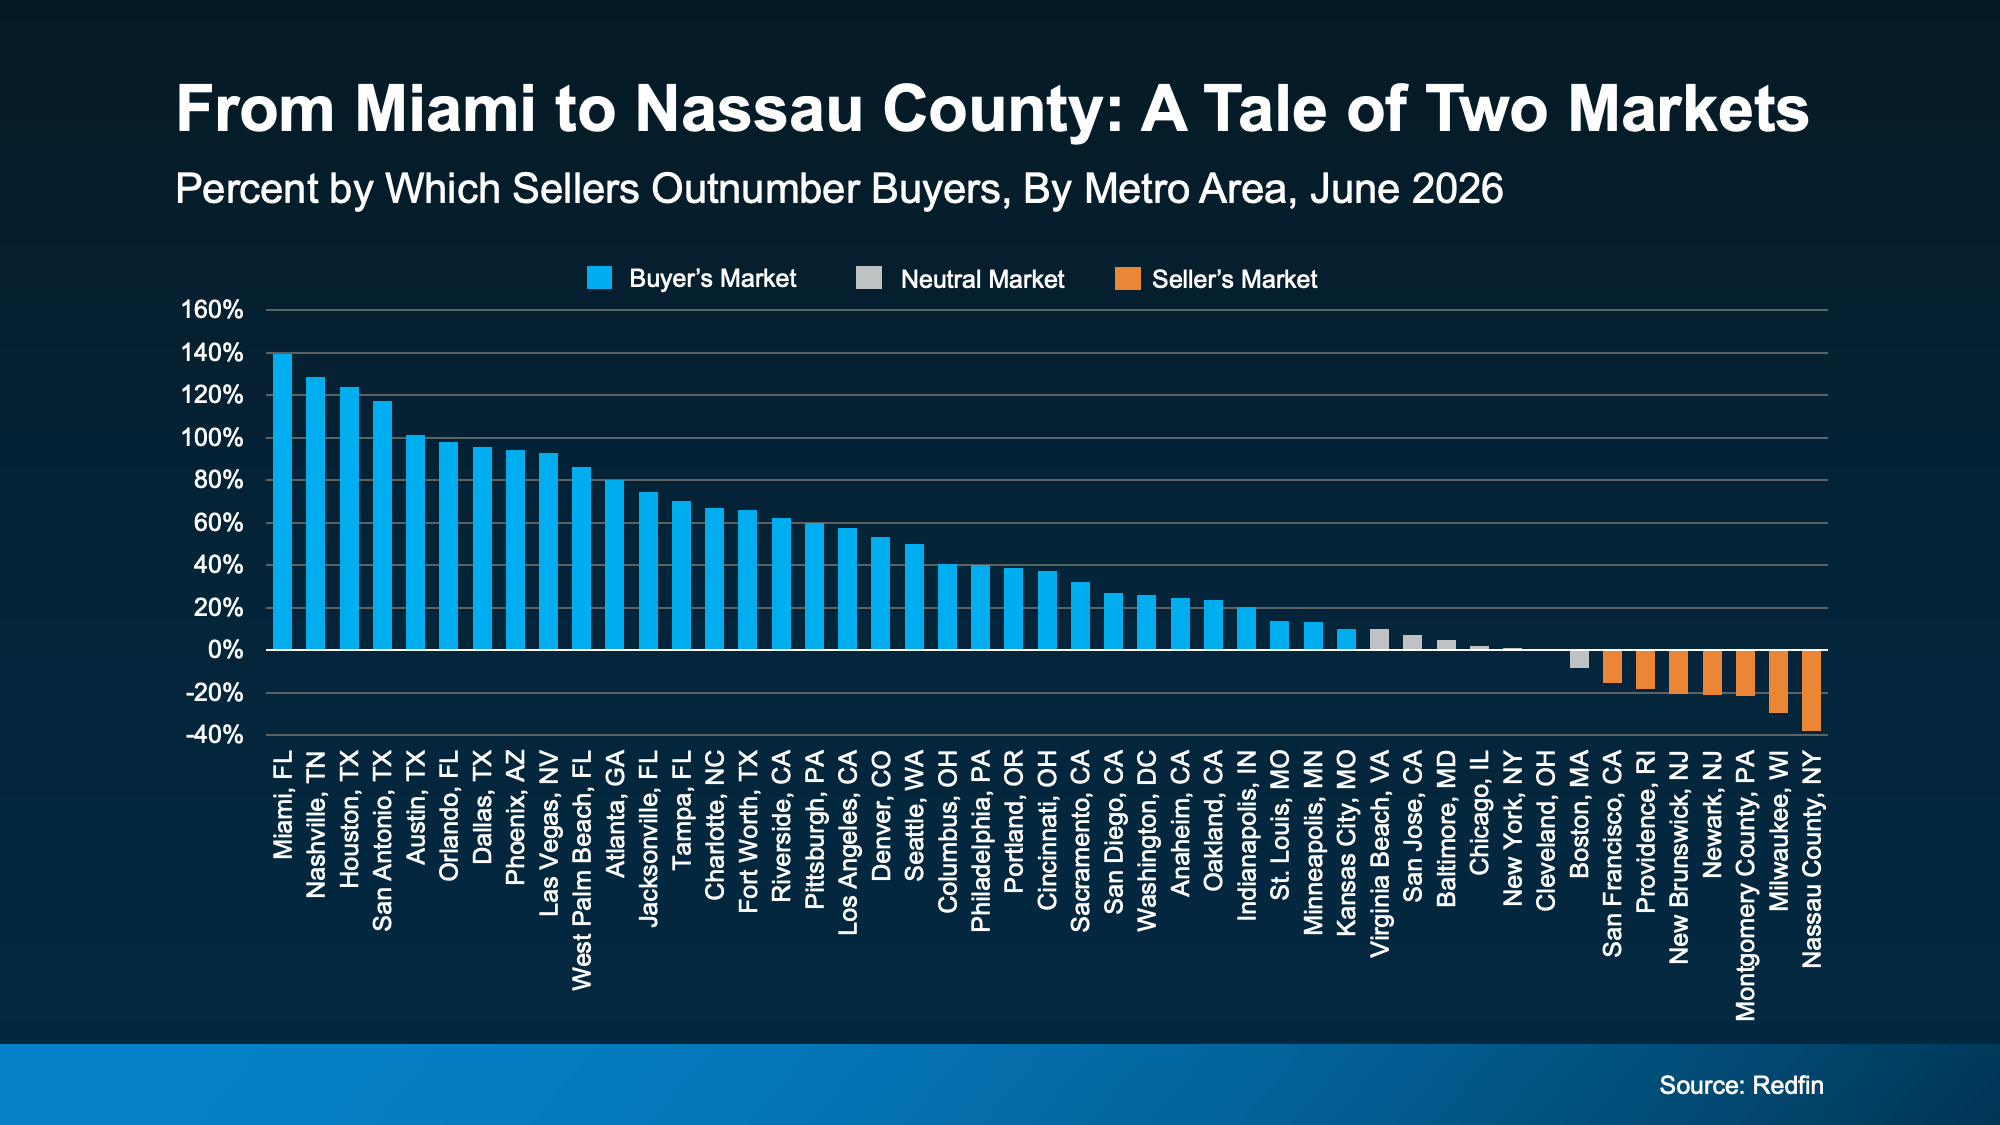
Redfin data helps shed some light on how this shakes out across the country. It breaks down which cities are leaning in either direction (see graph below).

  • Some markets give buyers more leverage. Those are in blue.

  • Some still favor sellers. That’s the orange.

  • Others fall somewhere in between. Those are gray. 

a graph of a marketNotice anything? A lot more places are seeing more buyer-friendly conditions right now.  In fact, this is the most buyer-friendly market we’ve seen in nearly 6 years.
But don’t take that as buyers have the upper hand everywhere.

There are still cities where sellers still have the power. And if you're in one of them, your approach to selling or buying looks completely different than it would in a buyer-leaning market.

The Biggest Mistake You Can Make Right Now

That’s why the biggest mistake isn't thinking it's finally a buyer's market. And it isn't thinking it's still a seller's market either. It's making any assumption without talking to an expert agent first.

Today’s market is incredibly local. In one market, a buyer may be getting thousands of dollars in concessions from a seller. And a homeowner may have to consider dropping their price.  

But in another, a buyer may be stressed about coming in with their best offer, or they may lose out on the home to another buyer. And a seller may still be seeing strong demand and prices inching higher.

Same overall housing market.

Very different experiences.

The truth is what’s happening in your back yard affects everything from pricing your house to making an offer to negotiating repairs or concessions. And that’s why an agent’s local knowledge matters more now than ever before.

Your plan has to be based on your neighborhood – and only an agent has the expertise to get that right.

Bottom Line

This market isn’t one-size-fits-all.

If you're wondering who has the upper hand where we live, let's talk. I'll show you exactly what the numbers look like in our market – and what strategy gives you the best shot at getting what you want.

Posted in Market Updates
Aug. 24, 2026

Thinking About Waiting for Lower Mortgage Rates? Read This First.


Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating.But it's a real possibility.

A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today's forecasts, that may not happen. And you should know that before you decide what to do.

Let's look at why experts don't expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.

1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way

If you're waiting for rates to fall, you're not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.

The challenge is, that's not what the experts who study mortgage rates every day are expecting.

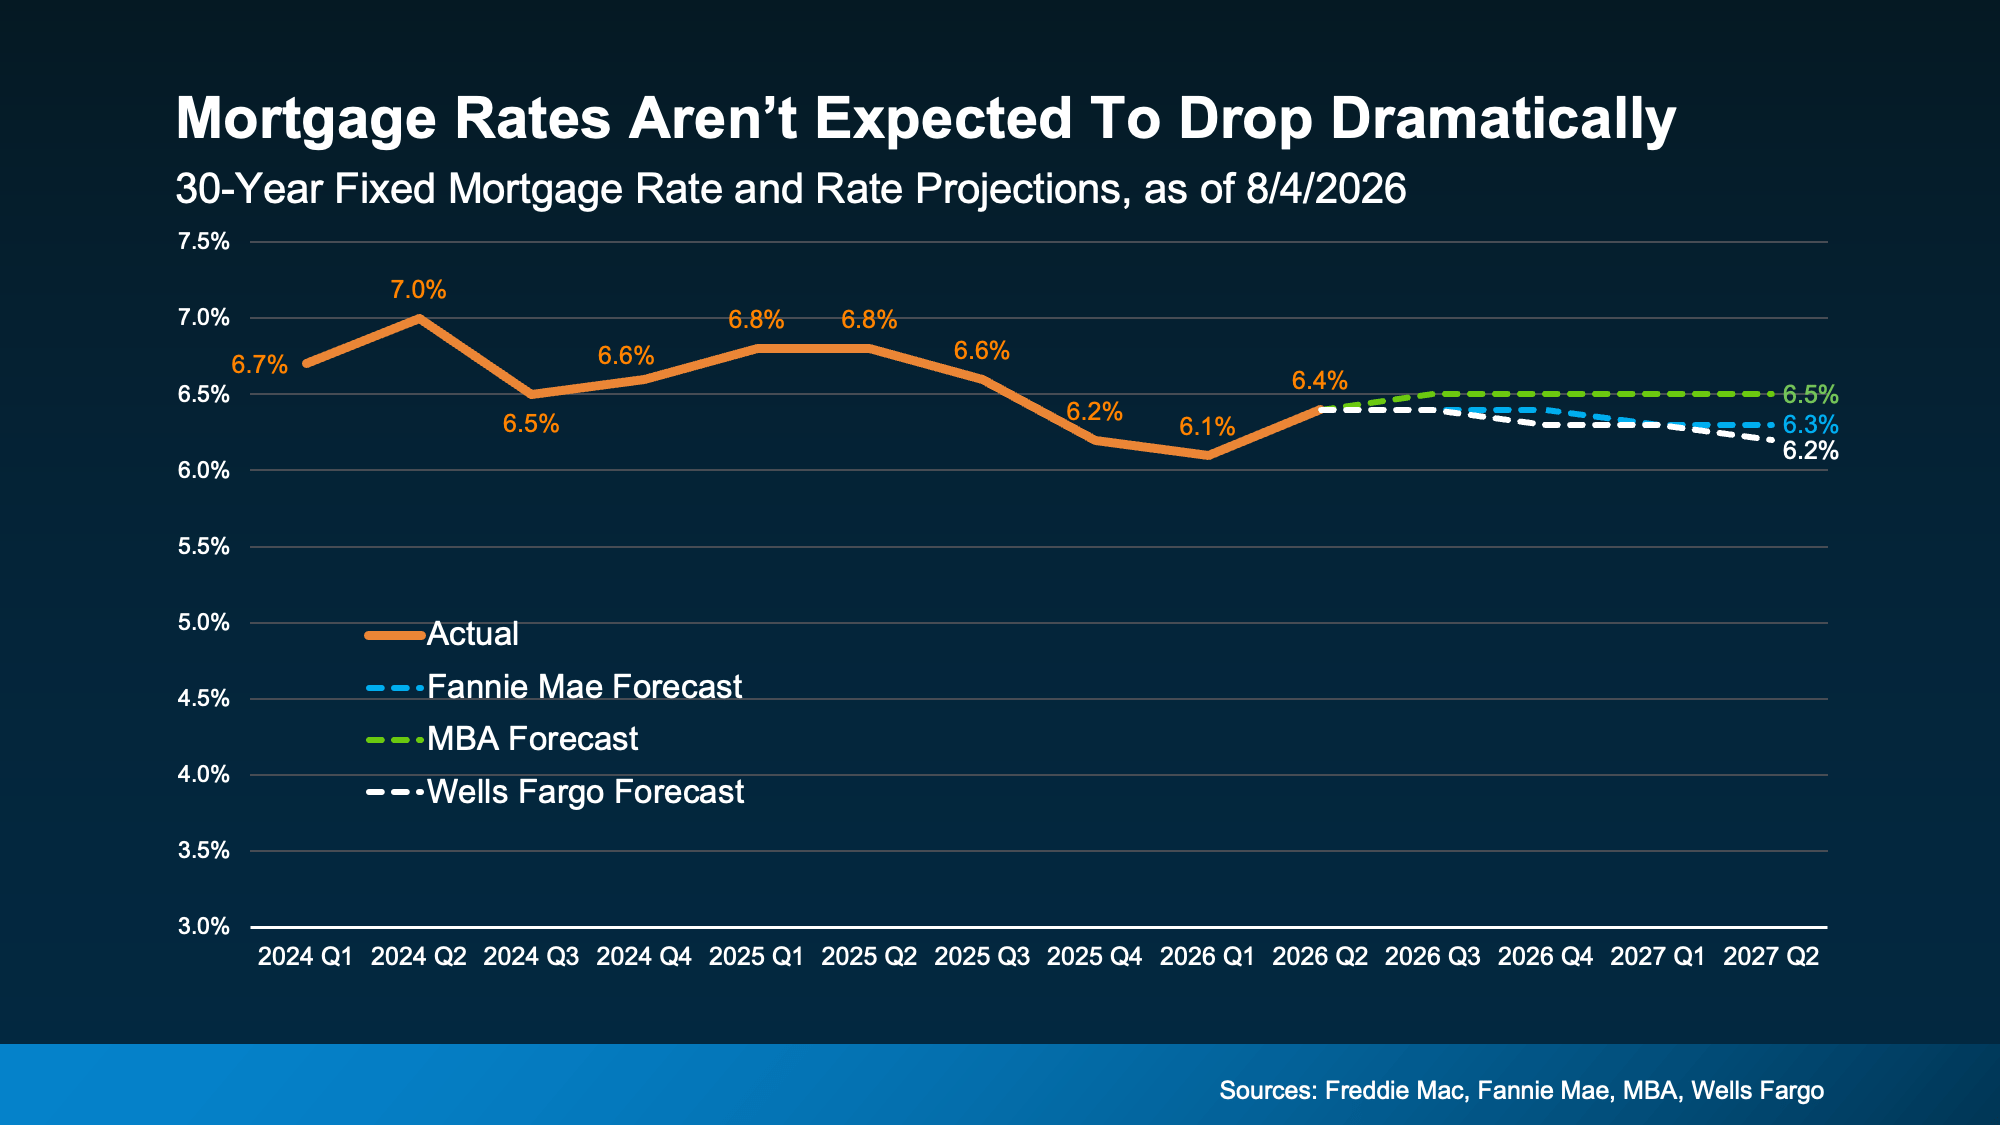
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):

a graph with numbers and lines

Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren't pointing toward the kind of dramatic rate drop many buyers are waiting for.

Could rates move a little? Of course. But if you're holding out for a bigger drop, today's forecasts suggest you may be waiting a lot longer than you expect.

2. Inflation Is Still Elevated – And That’s Working Against Lower Rates 

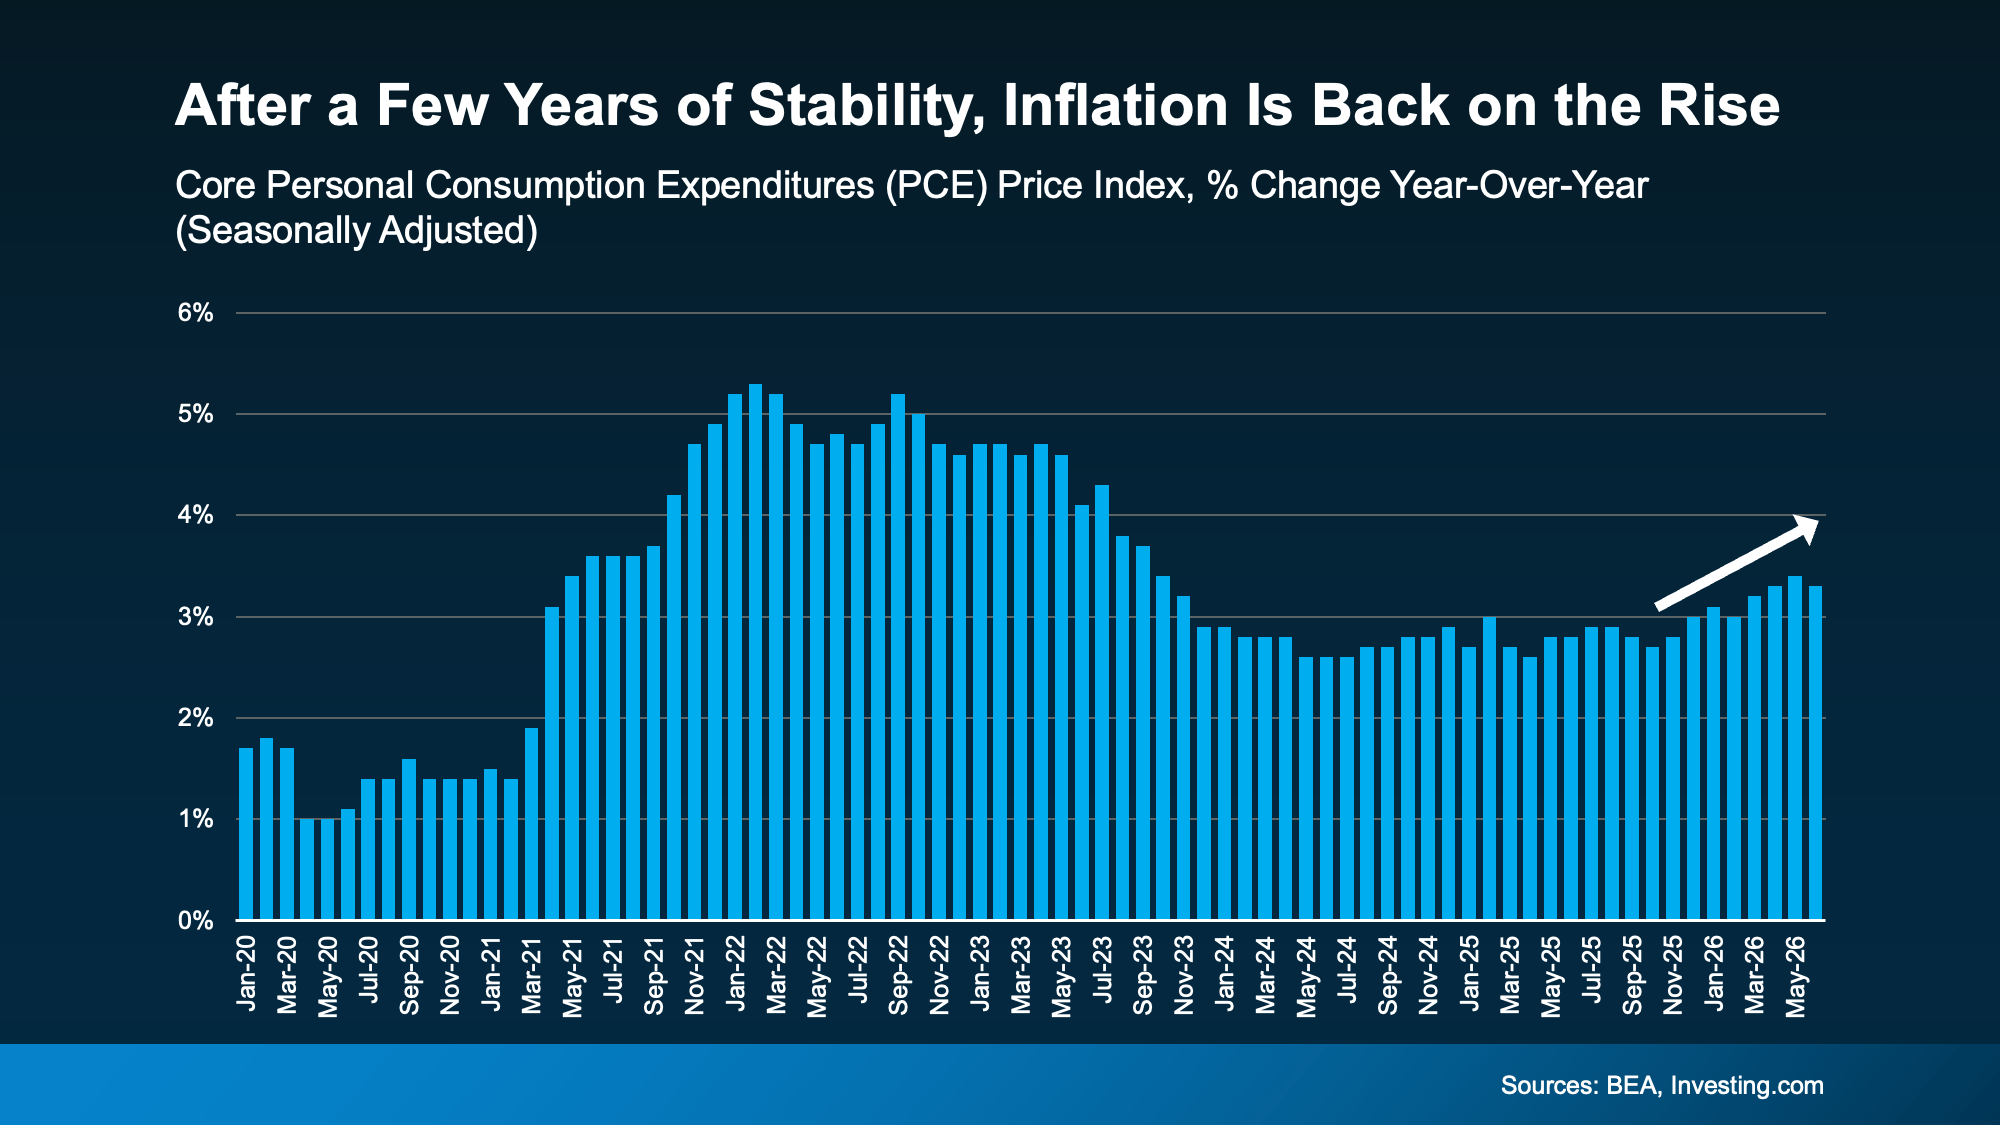
One reason experts aren't expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.

And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):

a graph of a number of people 

In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn't in place today. That helps explain why experts aren't forecasting the kind of meaningful decline so many buyers are hoping for.

3. Today’s Rates Aren’t High, They’re "Normal"

And this may be the biggest mindset shift of all. The reality is, while today's rates may feel high compared to a few years ago, they're not high. They’re normal.

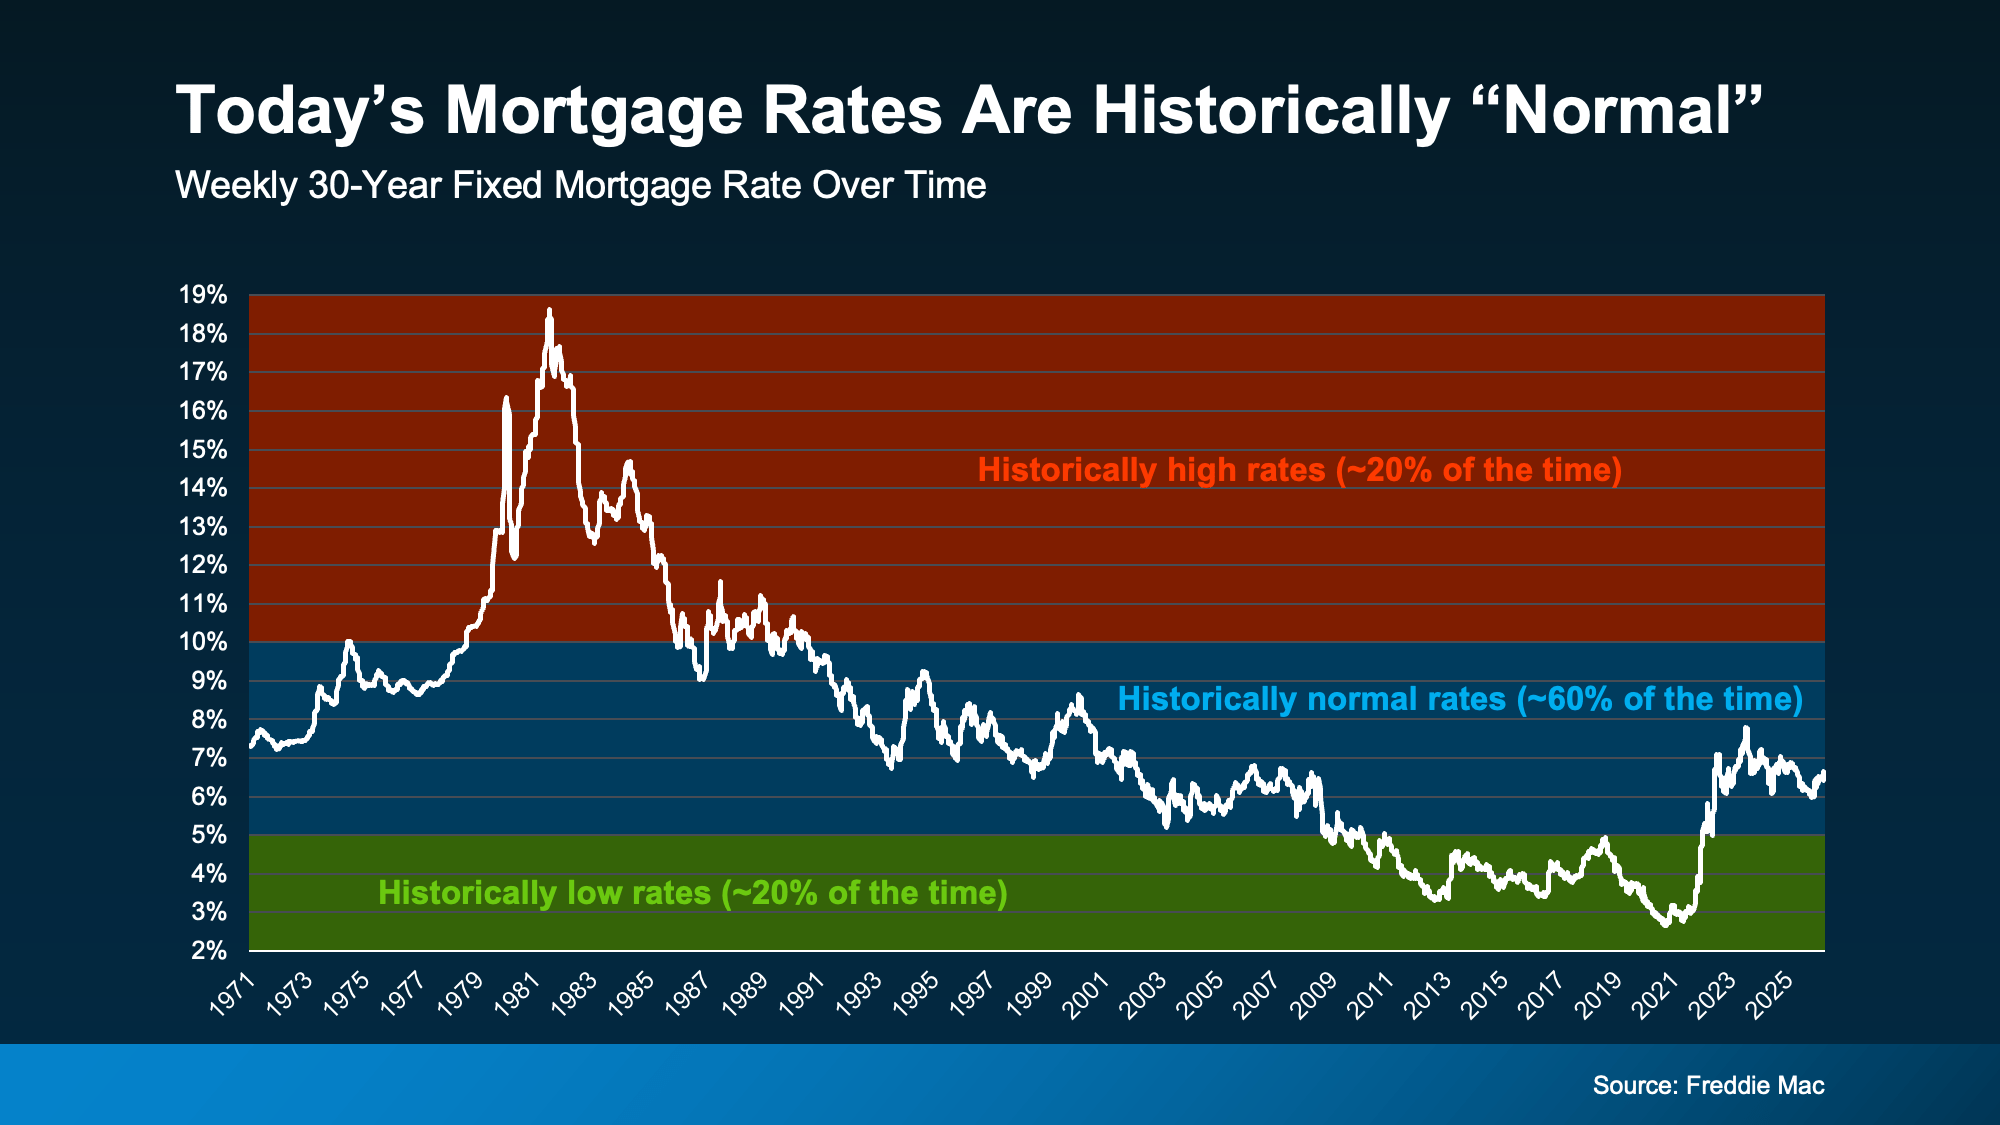
Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):

a graph of a graph showing the rise of a mortgage rate 

Now, this doesn't suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.

So... What Should You Do Instead?

None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.

  • Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.

  • Ask about an adjustable-rate mortgage (ARM). If you don't plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It's not the right choice for everyone, but it's worth asking a lender if it fits your plans.

  • Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.

  • Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.

The important thing is you shouldn’t assume waiting is your only option.

Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.

Bottom Line

If you've been putting your home search on hold because you're convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.

Let’s connect so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.

Posted in Market Updates
July 27, 2026

More Homes, Better Prices: Why This Summer Favors Buyers


If you've been thinking about buying a home over the past few years, you've probably faced two major challenges: rising prices and very limited inventory.


This summer, those conditions are beginning to shift. In many markets, asking prices are becoming more competitive, and buyers have more homes to choose from. Here's what that means for you.

Sellers Are Pricing Homes More Realistically

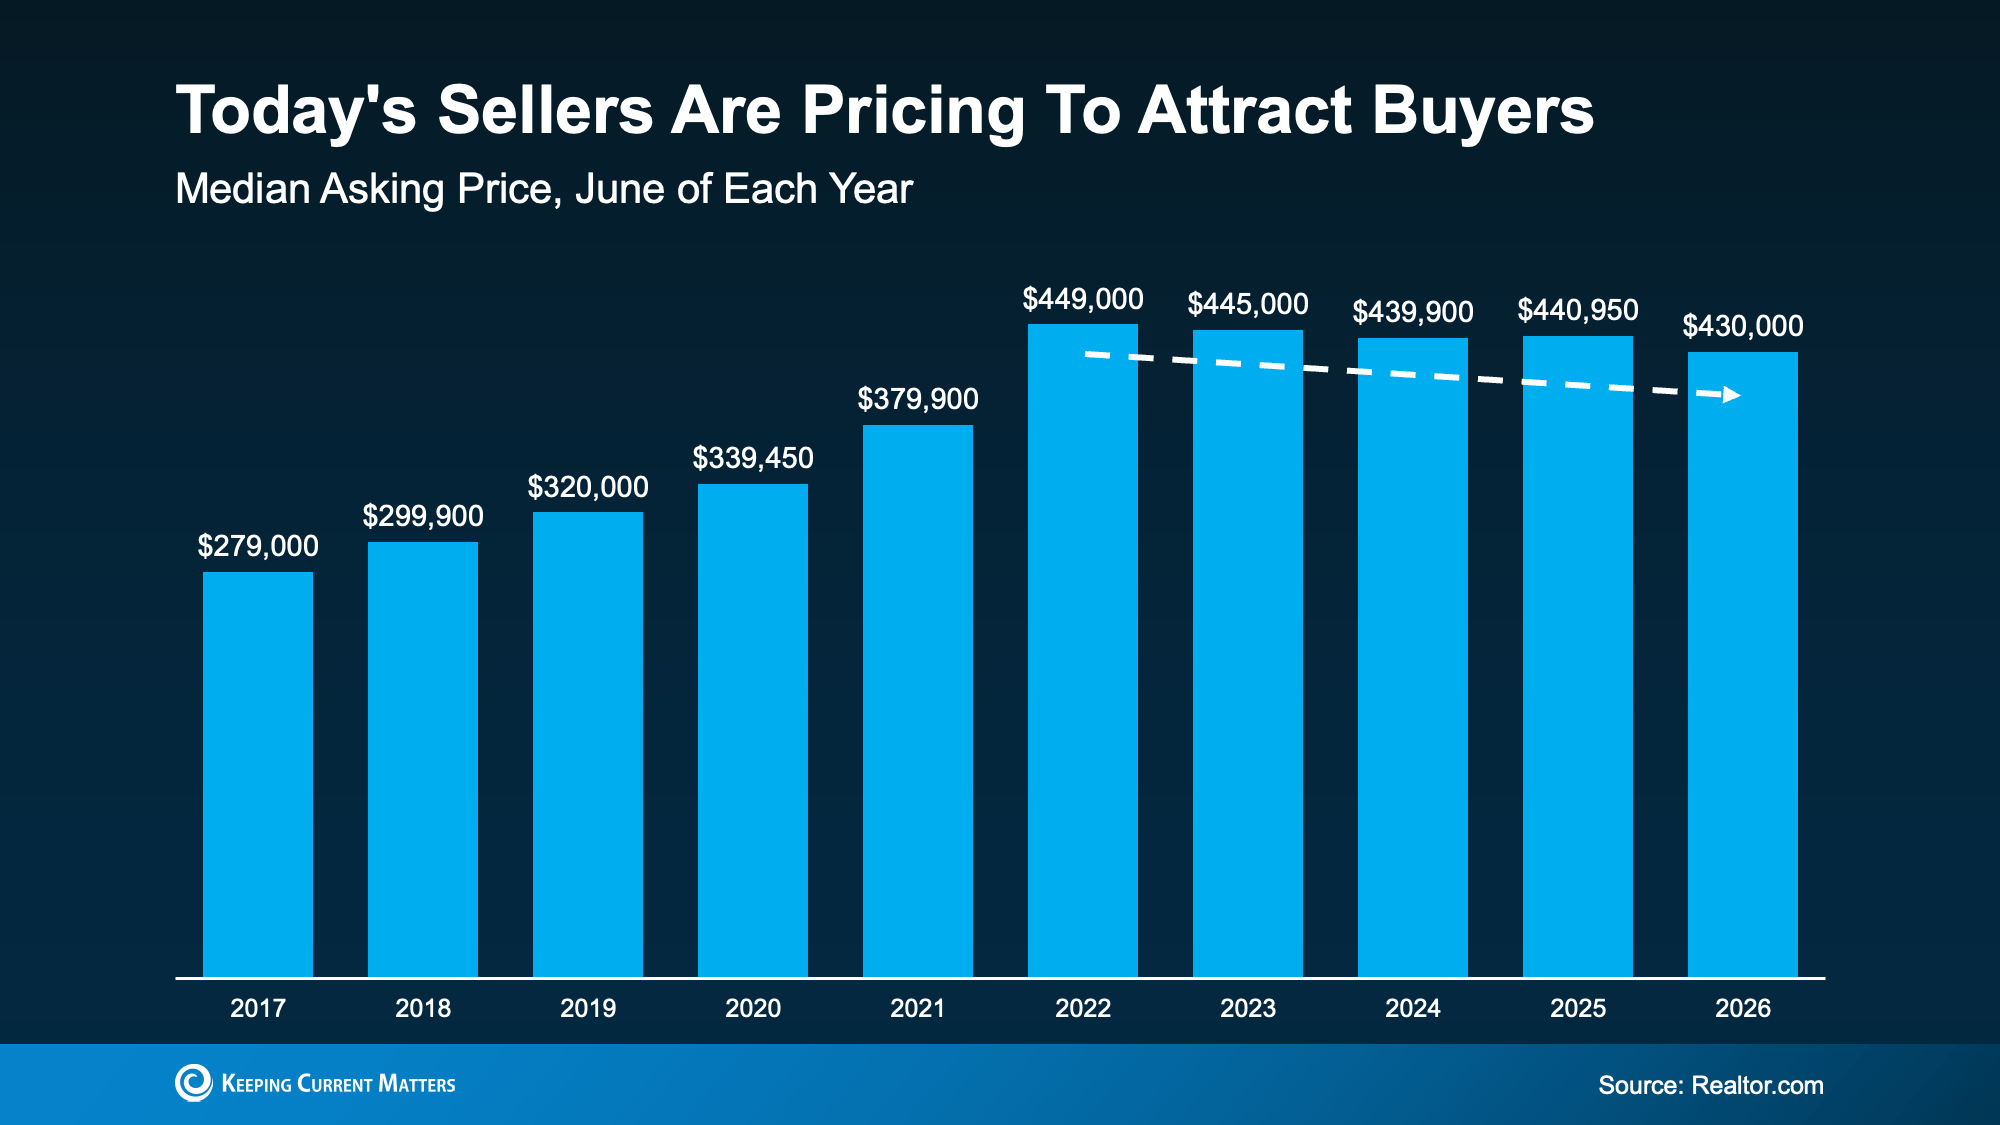
According to Realtor.com, the national median asking price was $430,000 in June, nearly $11,000 lower than it was a year earlier.

a graph of sales

This marks the eighth straight month that the typical asking price has been below the previous year's level.

That doesn't mean home values are crashing. These are asking prices, not final sales prices. Instead, it's a sign that sellers are adjusting to current market conditions and pricing their homes to attract buyers from the start.

As Danielle Hale, Chief Economist at Realtor.com, explains:

"Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market."


Rather than prices continuing to rise at an unsustainable pace, the market is settling into a healthier balance where buyers and sellers are finding more common ground.

Buyers Have More Homes To Choose From

If you've been frustrated by homes selling before you even had a chance to schedule a showing, there's good news.

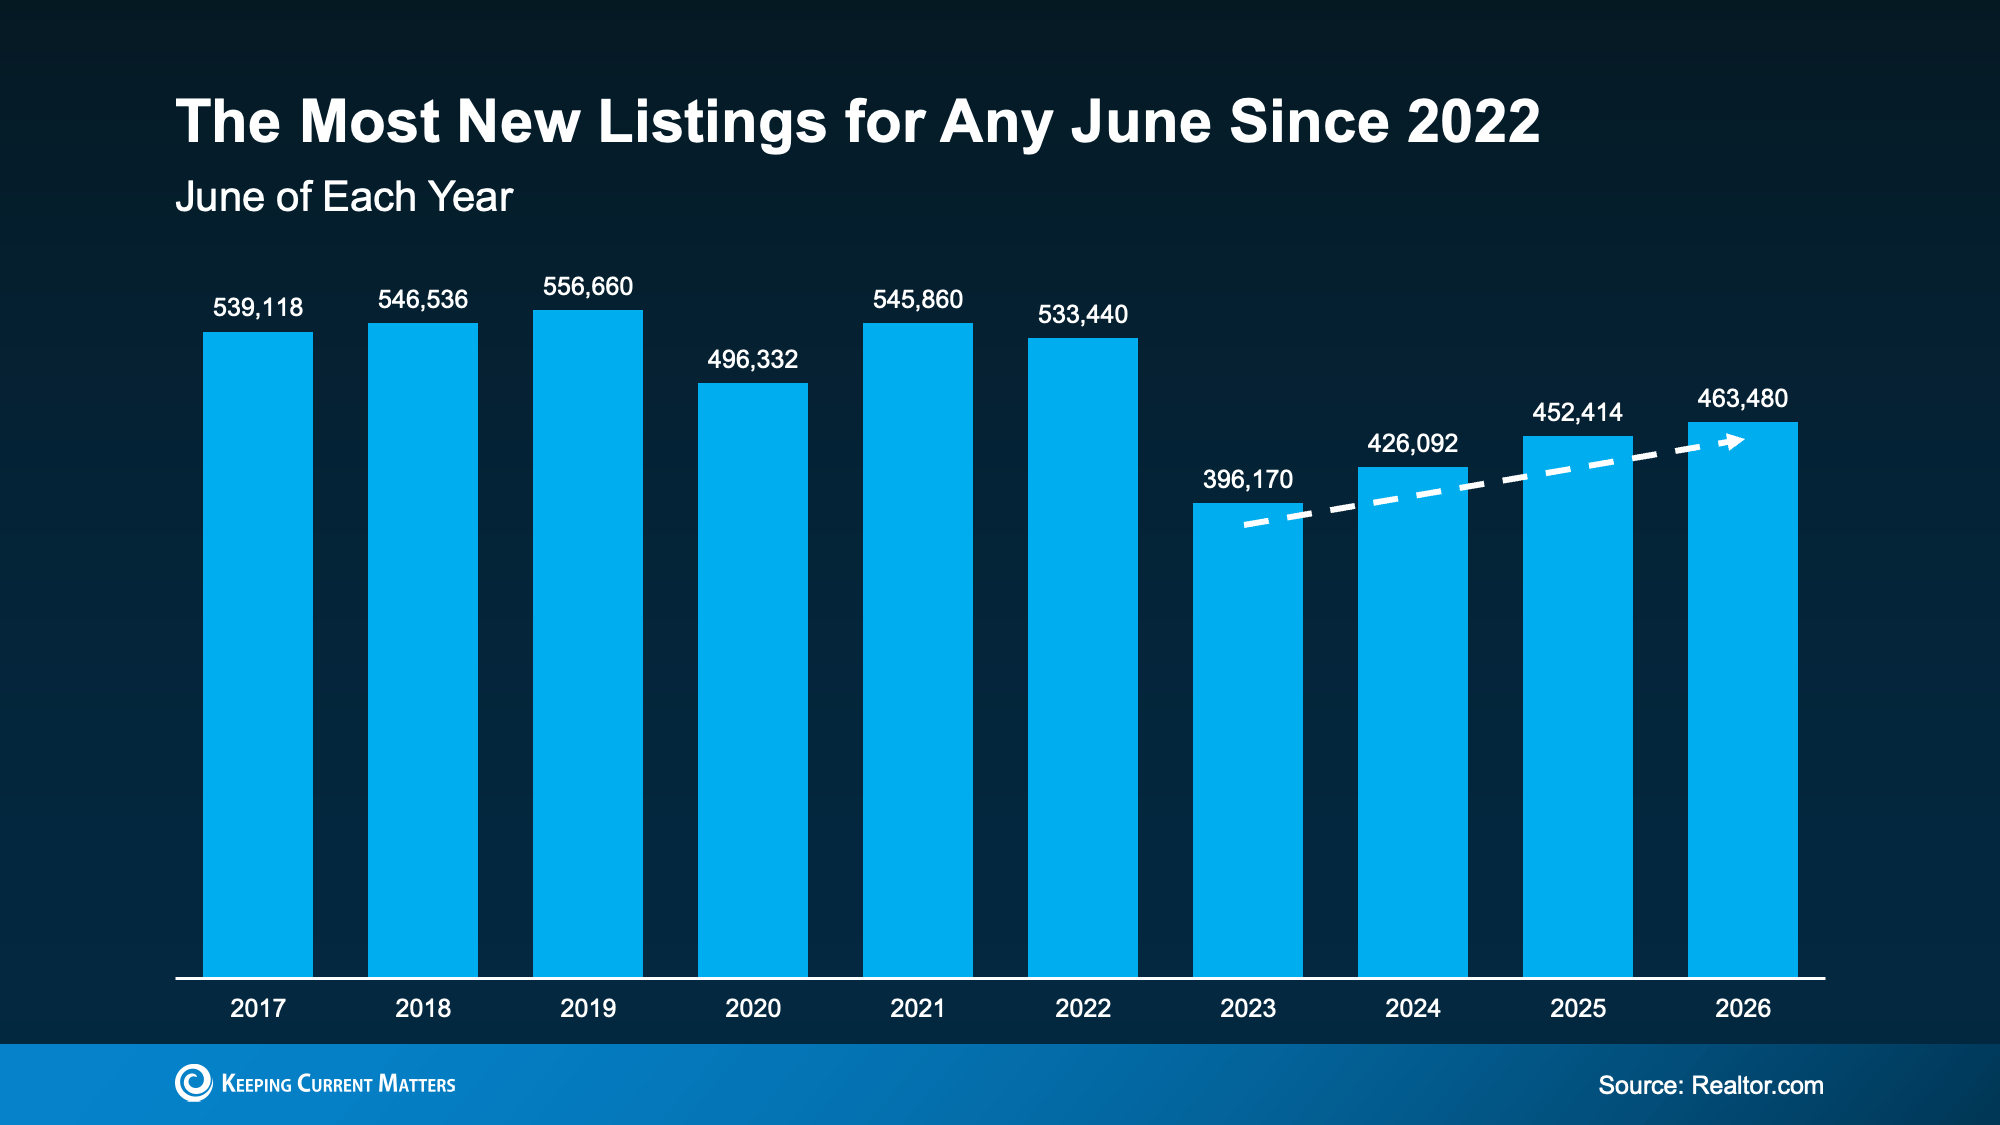
According to Realtor.com, June recorded the highest number of homes for sale during the month of June in the past three years.

a graph with numbers and a number of blue bars

While inventory still hasn't returned to pre-2020 levels in many areas, buyers now have far more choices than they did just a year ago.

More inventory means:

  • More homes that fit your needs
  • Less competition from other buyers
  • More time to make thoughtful decisions
  • Greater negotiating power during the purchase process

Instead of feeling pressured to make an immediate offer, buyers have more opportunity to compare properties and find the right fit.

Great News for First Time Buyers

These market trends are especially encouraging for first time buyers.

According to Zillow Chief Economist Mischa Fisher:

"The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing activity growth, the first time since 2022 that's been the case."


In other words, entry level homes are seeing both increased inventory and more price flexibility, making it a better environment for buyers trying to purchase their first home.

Bottom Line

If higher prices and limited inventory have kept you on the sidelines, this summer may be the opportunity you've been waiting for.

With more homes available and sellers pricing more competitively, buyers have more options and more leverage than they've had in quite some time.


If you're ready to explore what's available in your local market, connect with a trusted real estate professional and start your search with confidence.

Posted in Market Updates
July 27, 2026

Priced Out? A Condo or Townhome Might Be the Opportunity You're Looking For.

With home prices still higher than many buyers expected, it's easy to feel like homeownership is out of reach. Especially if you're buying for the first time.

But that doesn't always mean you have to put your plans on hold. Sometimes, it simply means looking at a different type of home.


Condos and townhomes can offer a more affordable way to become a homeowner. And right now, there are two big reasons they're worth considering.

There Are More Condos and Townhomes Available

If your search for a single family home hasn't turned up many good options, it may be time to expand your search. Many buyers automatically focus on detached homes and overlook condos and townhomes, even though they can offer great value.

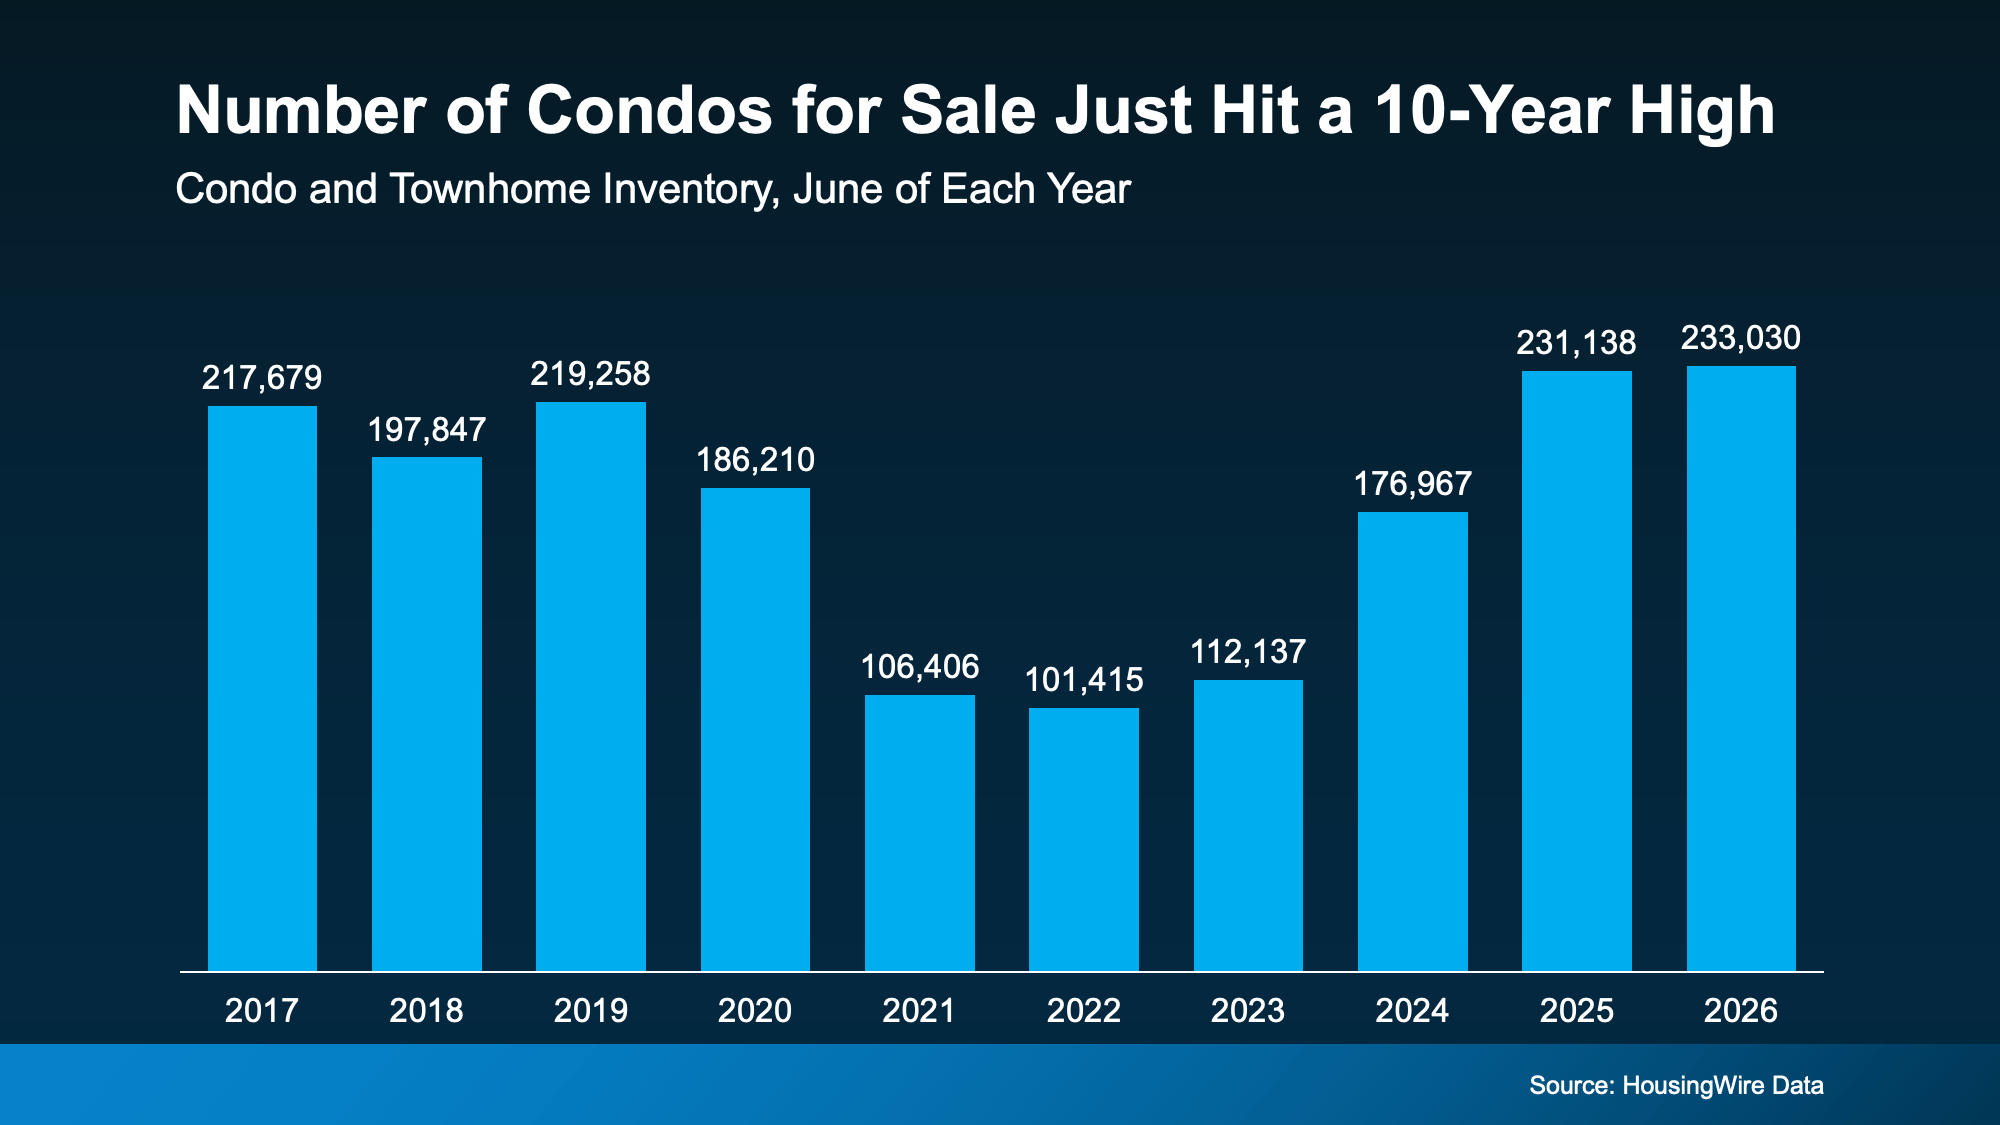
According to HousingWire Data, there were 233,030 condos and townhomes on the market this June. That's the highest June inventory in at least the past decade and more than twice as many as were available in 2022.

a graph of blue bars

With more homes to choose from, buyers often have more flexibility, less competition, and a better chance to negotiate.


Keep in mind that inventory varies by market, but overall, buyers have more opportunities in this segment than they have in years.

They Usually Come With a Lower Price Tag

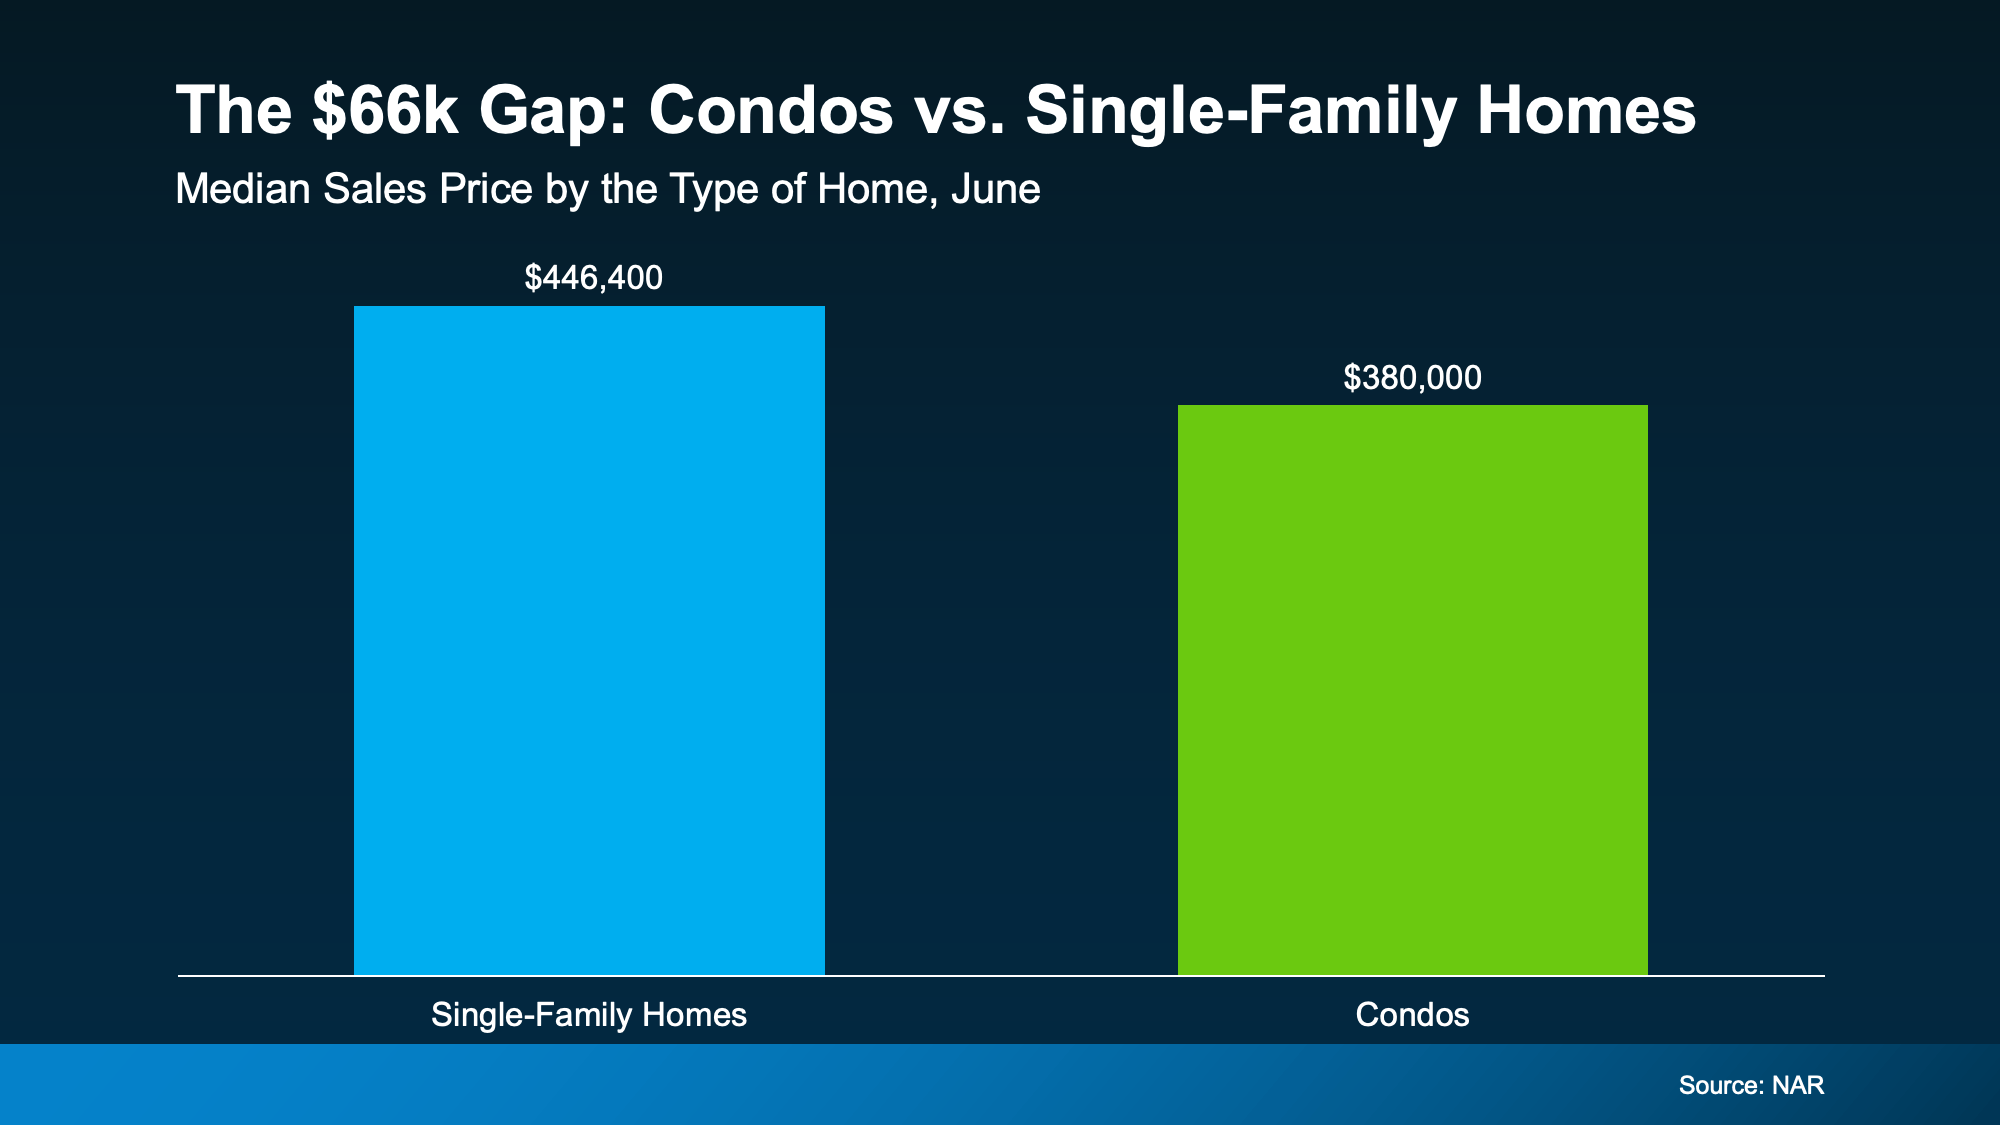
Affordability is another major advantage. According to the National Association of Realtors (NAR), the median condo price in June was $380,000, while the median single family home price reached $446,400.

That's a savings of more than $66,000. One reason is simple. Condos are typically smaller than detached homes, making them a more budget friendly option for many buyers.

If you don't need extra bedrooms or a large yard, choosing a smaller home could make buying much more attainable.a graph of a chart

Condo vs. Townhome: What's the Difference?

If you're deciding between the two, here's a quick comparison.

Single Family Home

You own both the home and the land beneath it. There are no shared walls, giving you the most privacy and space. You'll also be responsible for all maintenance and repairs, and these homes typically come with the highest purchase price.

Townhome

You own the home and the lot it sits on. Most townhomes have multiple levels and share one or two walls with neighboring homes. They often provide more living space than condos while still offering a lower price than many detached homes. Owners generally handle more of the maintenance.

Condo

You own the interior of your unit, while the building and shared amenities are maintained by the homeowners association. Many condos include access to features like pools, fitness centers, or clubhouses. They usually require less maintenance, though you'll have HOA fees and less control over exterior decisions.

Bottom Line

If buying a single family home feels out of reach right now, a condo or townhome could be a smart first step toward homeownership.


With more inventory and generally lower prices, now may be a great time to explore all your options. Connect with a local real estate professional to see what's available in your area and find the home that best fits your needs and your budget.

Posted in Market Updates