


That kitchen you’ve been mentally redesigning...
The bathroom that really needs a refresh...
Or the outdoor space you keep saying you’ll get to someday...
What if you already have what you need to finally make it happen? Because a growing number of homeowners are realizing just that.
Homeowners are expected to spend over $522 billion on home improvements by the end of 2026 – and they’re not draining their savings accounts to get it done. Many are using their home equity.
And if you’ve owned your home for 10+ years, there’s a chance you could use your equity to fund some home upgrades too. Let’s break down what you need to know first.
What Is Equity? And How Does It Help?
Equity is the difference between what your house is worth and what you owe on your mortgage.
And according to Cotality, the average homeowner has about $313,000 worth of equity today. That’s more than enough to finally knock some projects off your list. And more people are realizing they can use that to give their home a little TLC.
Research coming out of Meridian Link says home improvements are the top thing people are using their equity for today.
Top Motivations for Equity-Based Borrowing:
- Funding home improvements (45%)
- Using it to pay down other debts / debt consolidation (16%)
- Investing in other properties (16%)
Maybe it makes sense for you to do the same. But here’s what’s important. Just because you can use your equity doesn’t mean you have to. It also doesn’t mean every project makes sense.
What Projects Are Actually Worth It?
If you’re going to go this route, you’ll want to focus on upgrades that actually pay off. A good renovation should be something that improves the value of your home. Because, even if you’re not planning to sell soon, you want to make sure you’re setting yourself up for success when you do.
And an agent is the best resource as you weigh your options. They know what other homeowners are doing and what buyers in your area like. And that can be really helpful as you narrow down your project list. As the National Association of Realtors (NAR) puts it:
“Being able to help sellers prioritize home improvements and maximize their net on the sale is a key value real estate agents offer.”
Here’s a quick rundown of the projects with the best potential to recoup your costs according to NAR (see graph below). While it’s a good starting point, just remember it can’t match the expertise an agent can provide.
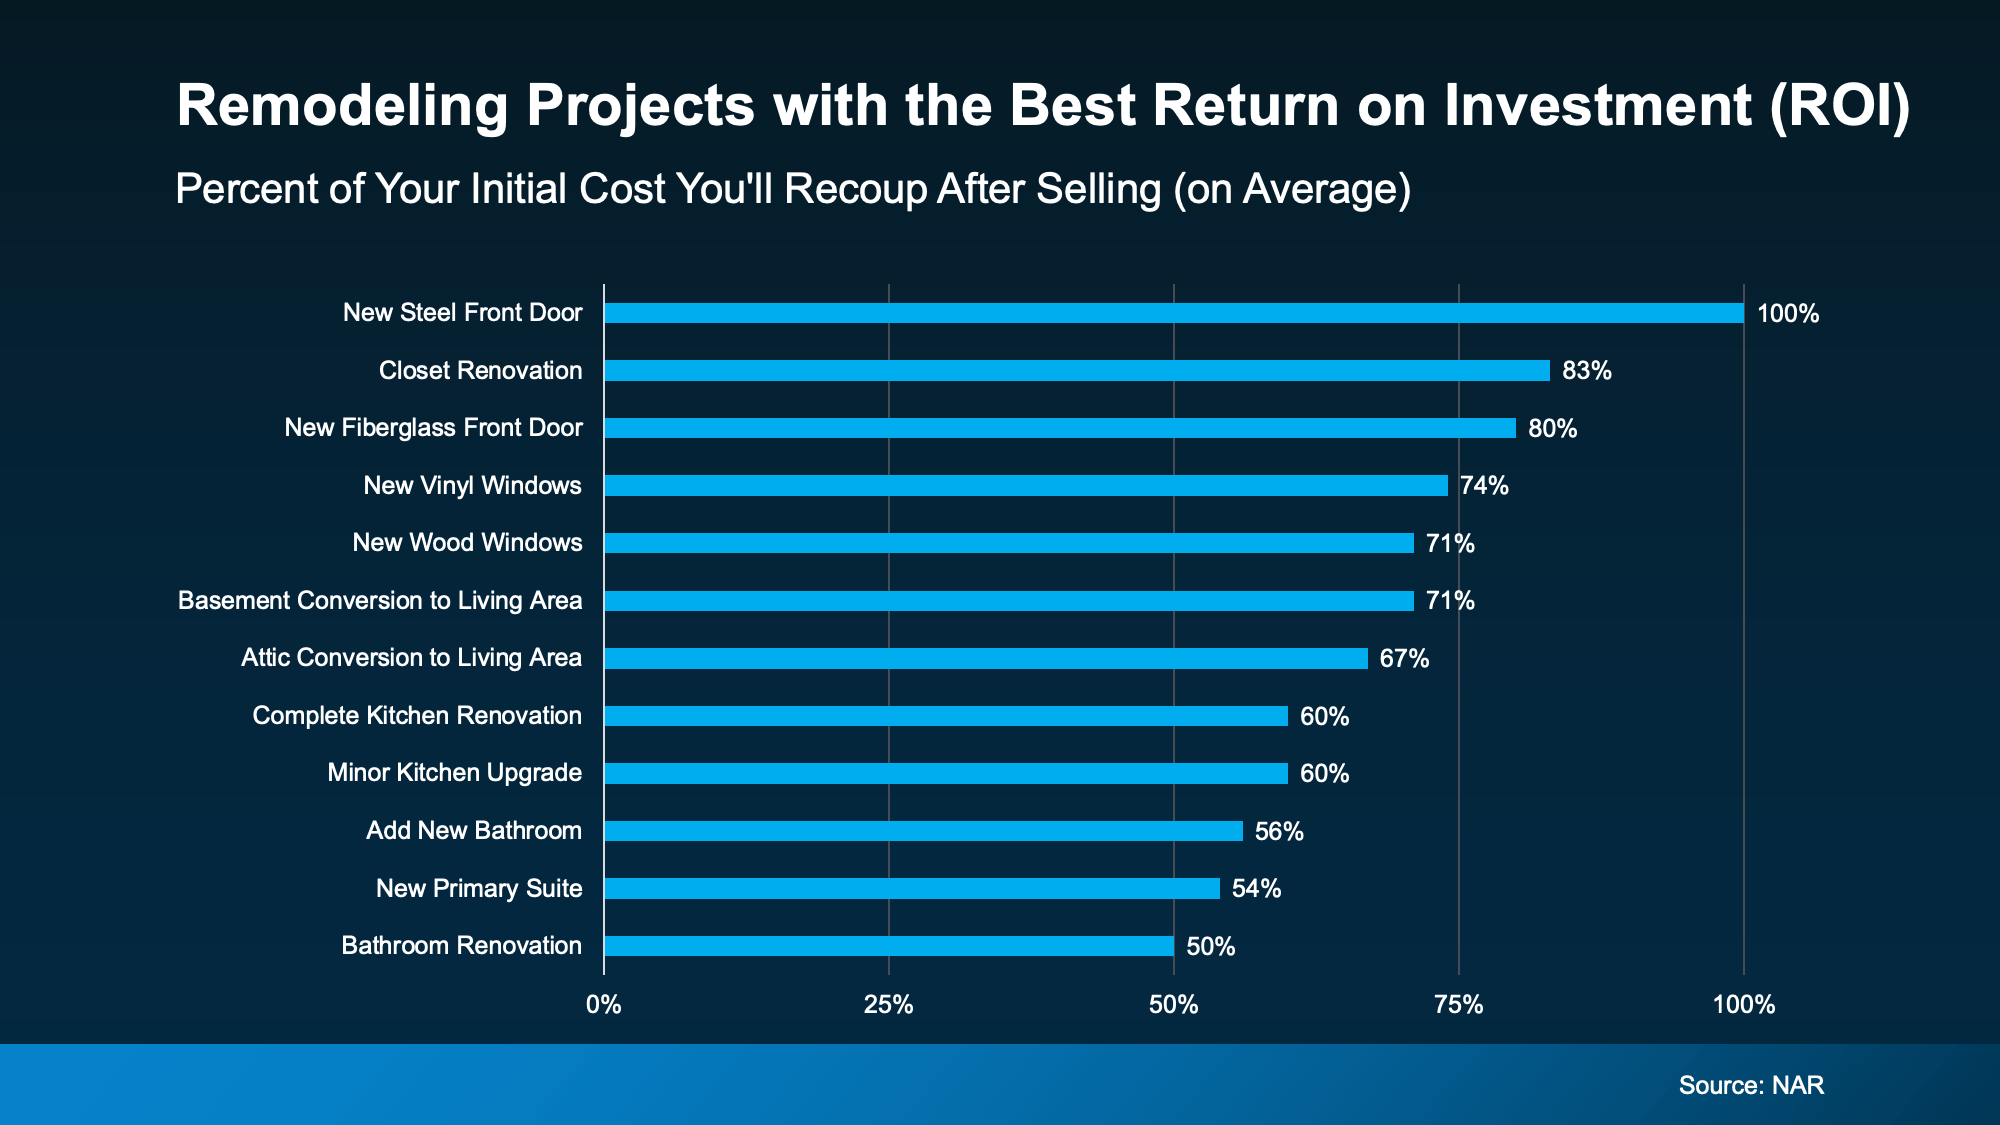 As you can see, there’s a wide range of projects on that list. Yes, some are bigger-ticket items, like kitchens or baths. But others are smaller updates with surprisingly strong ROI.
A new front door is a great project. But it’s not something to use your equity for. But revamping your kitchen? That’s where your equity can come in and lighten the load.
Where To Go from Here
Whether the project you’ve been thinking about is on this list or not, chat with an agent to make sure it’s worth the time, money, and effort before calling in any contractors.
Because the goal isn’t to do everything, it’s to invest where it counts.
And if you want to use your equity to get one of the bigger projects done, meet with a financial advisor too. Because you’ll want to make sure you’ll maintain a good loan-to-value (LTV) threshold even after using your equity. That way you have all the information you need to make your decision.
Bottom Line
Whether you’re selling next year or just giving your house some TLC, the right home improvements today can set you up for success tomorrow. And the best part? Your equity may be the key to making it happen.
What’s one upgrade you’ve been thinking about – and wondering if it’s worth it?
Let’s have a quick conversation about whether it’s the right decision for your home.
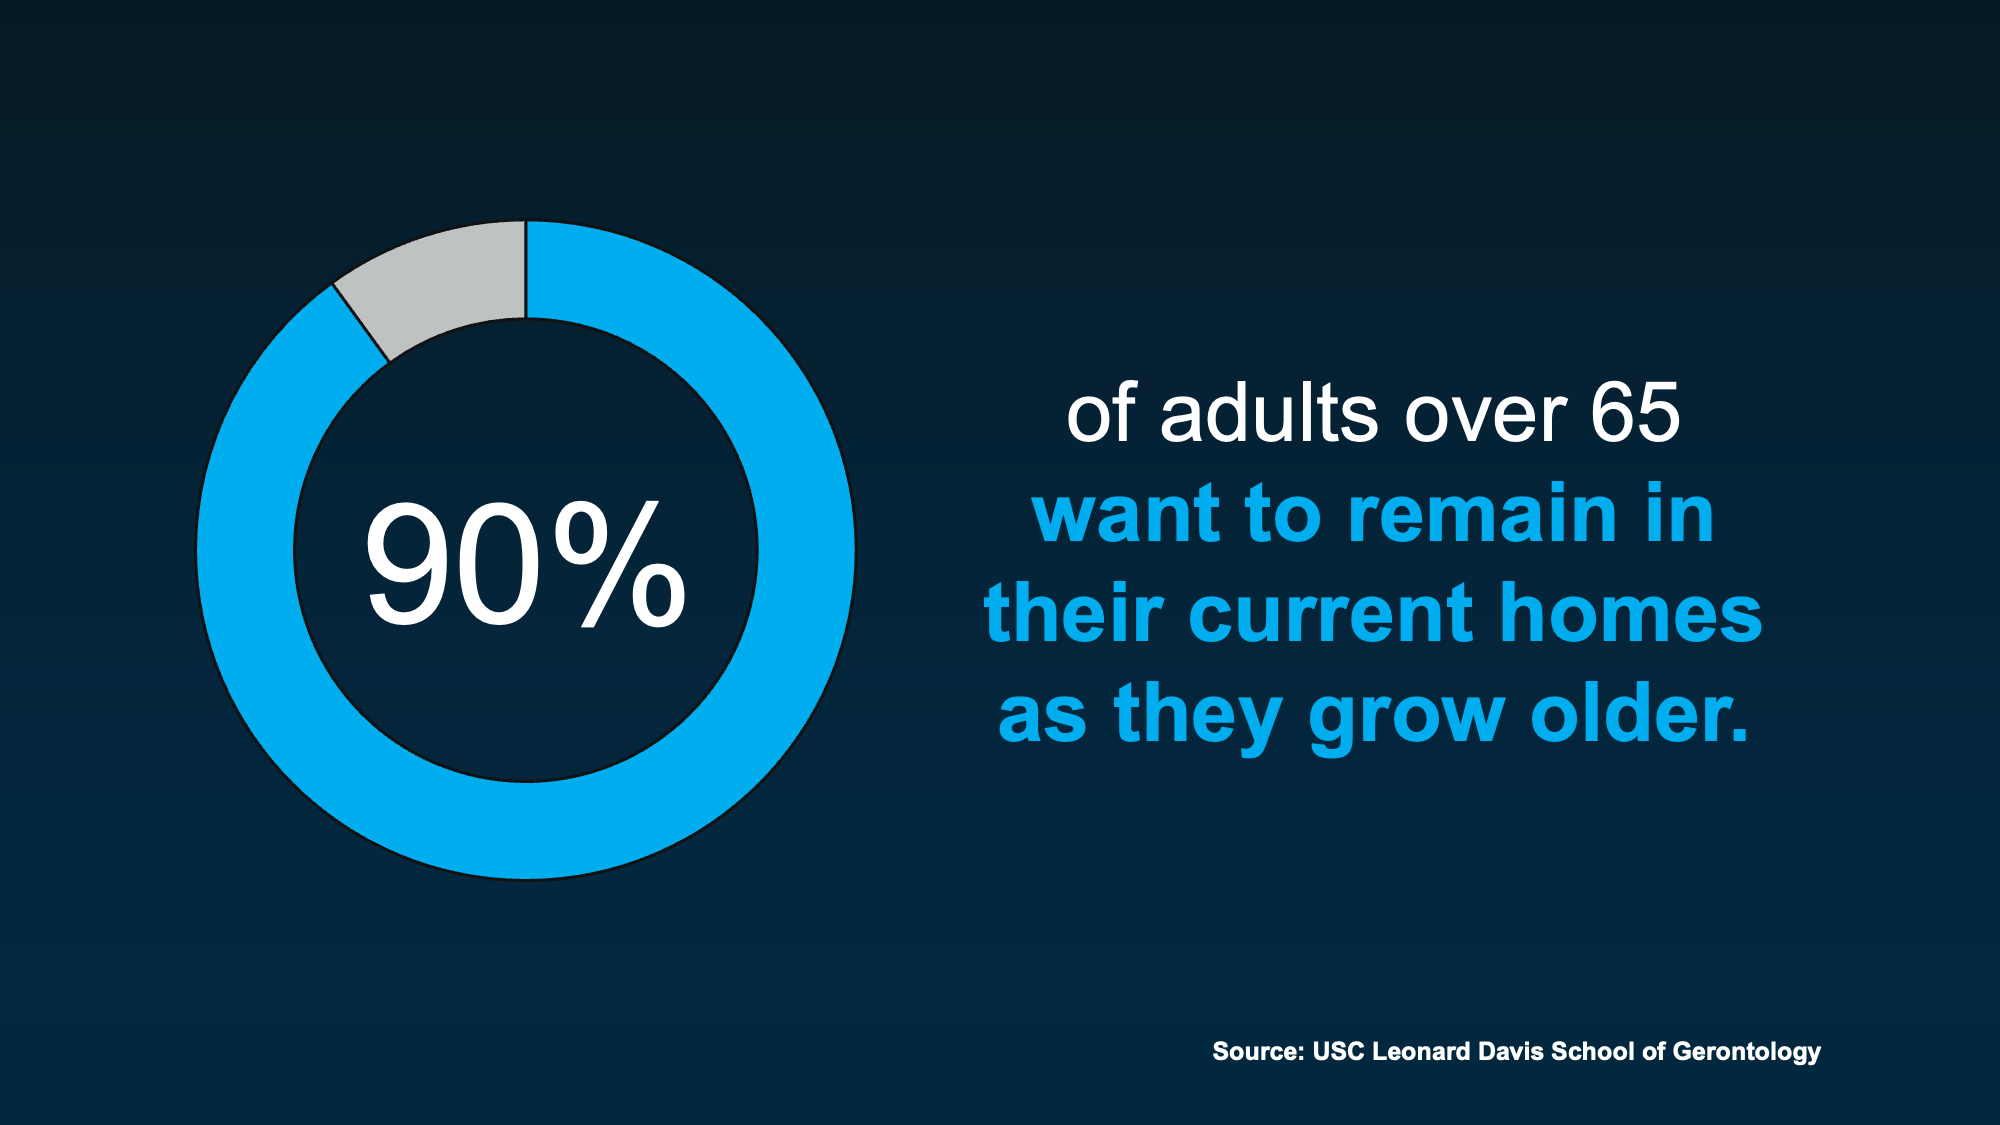 But even if staying feels like the right answer, it’s still worth thinking ahead about what that might actually look like. That’s where the right agent can really help.
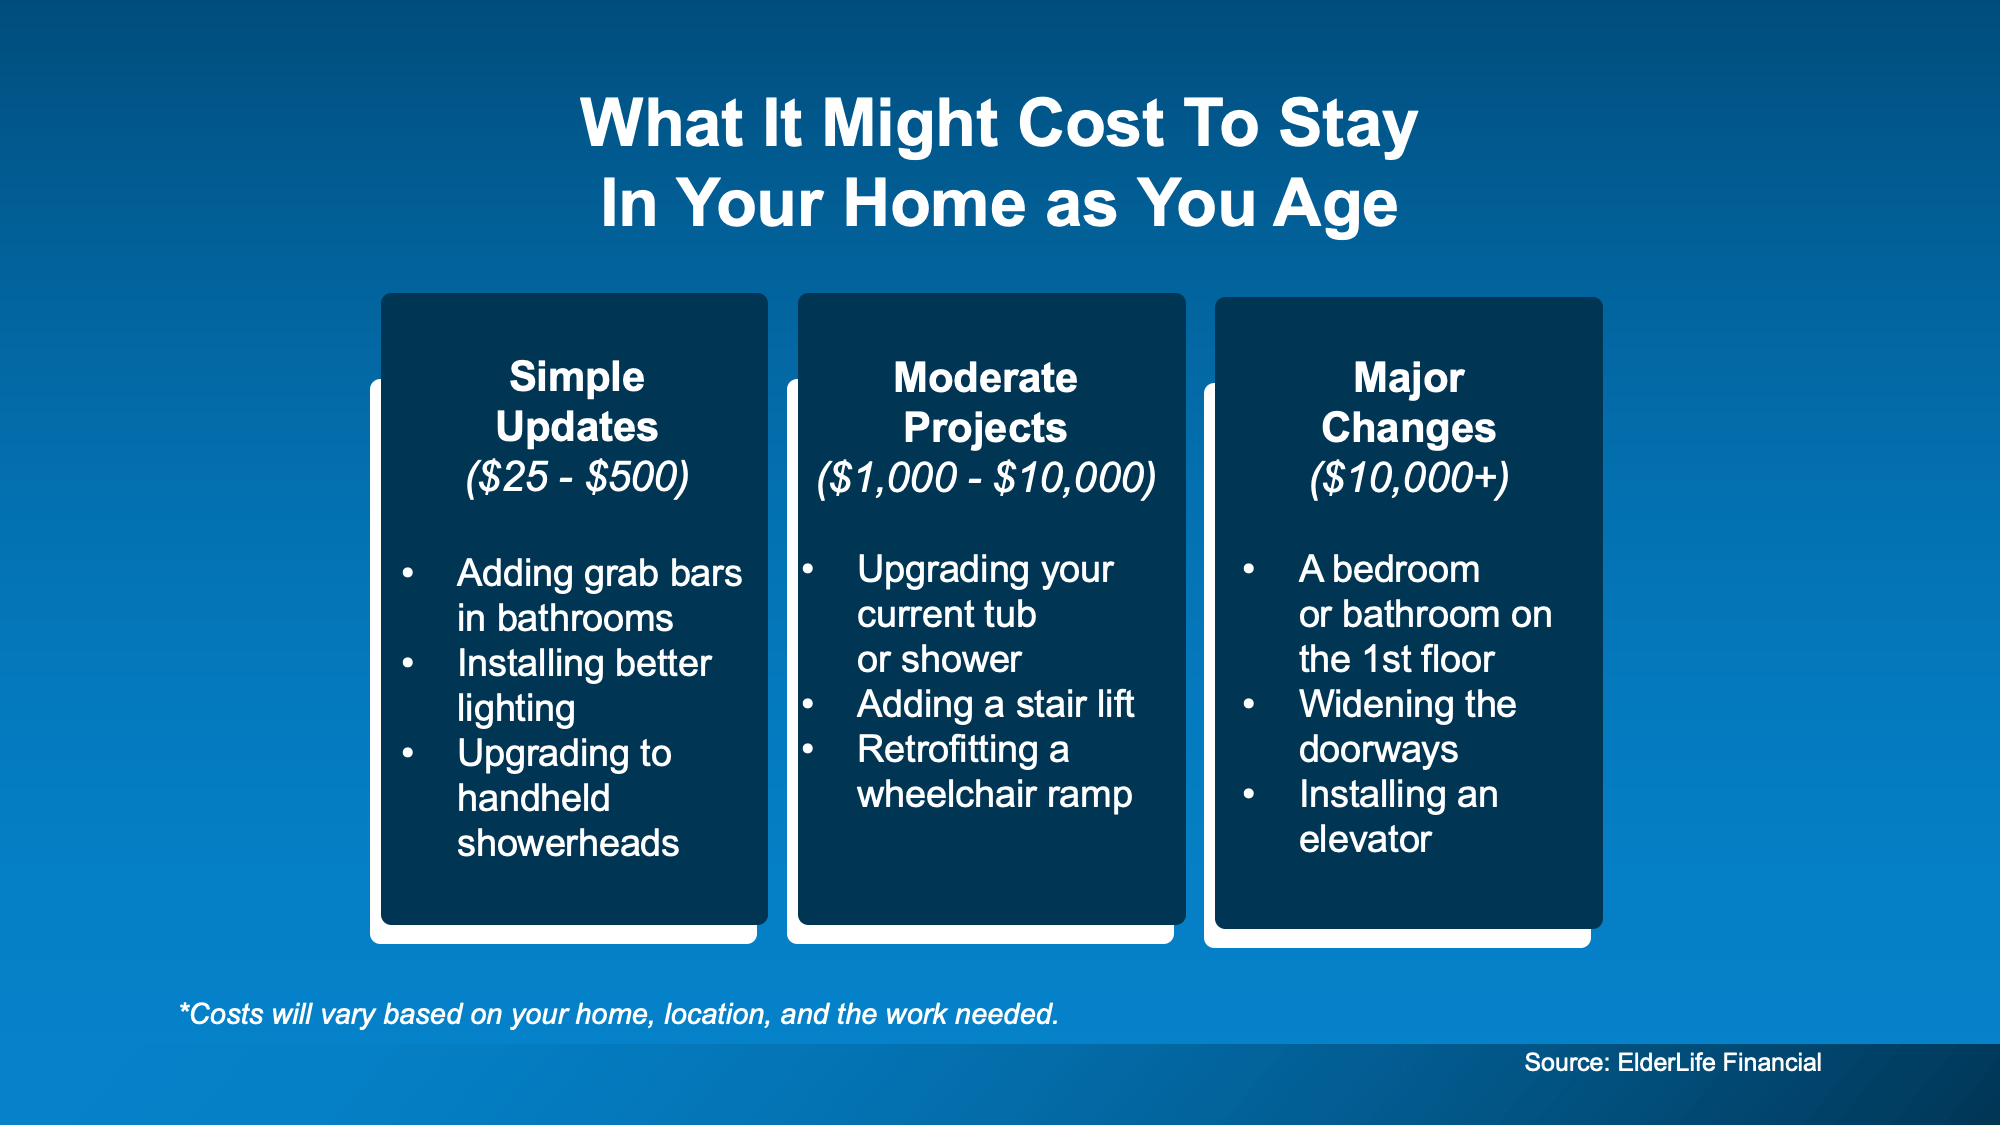 And don’t worry. If your heart is really set on staying, but the costs feel like a concern, it helps to know you have options. Depending on your situation, there may be financial assistance programs available, along with tools like
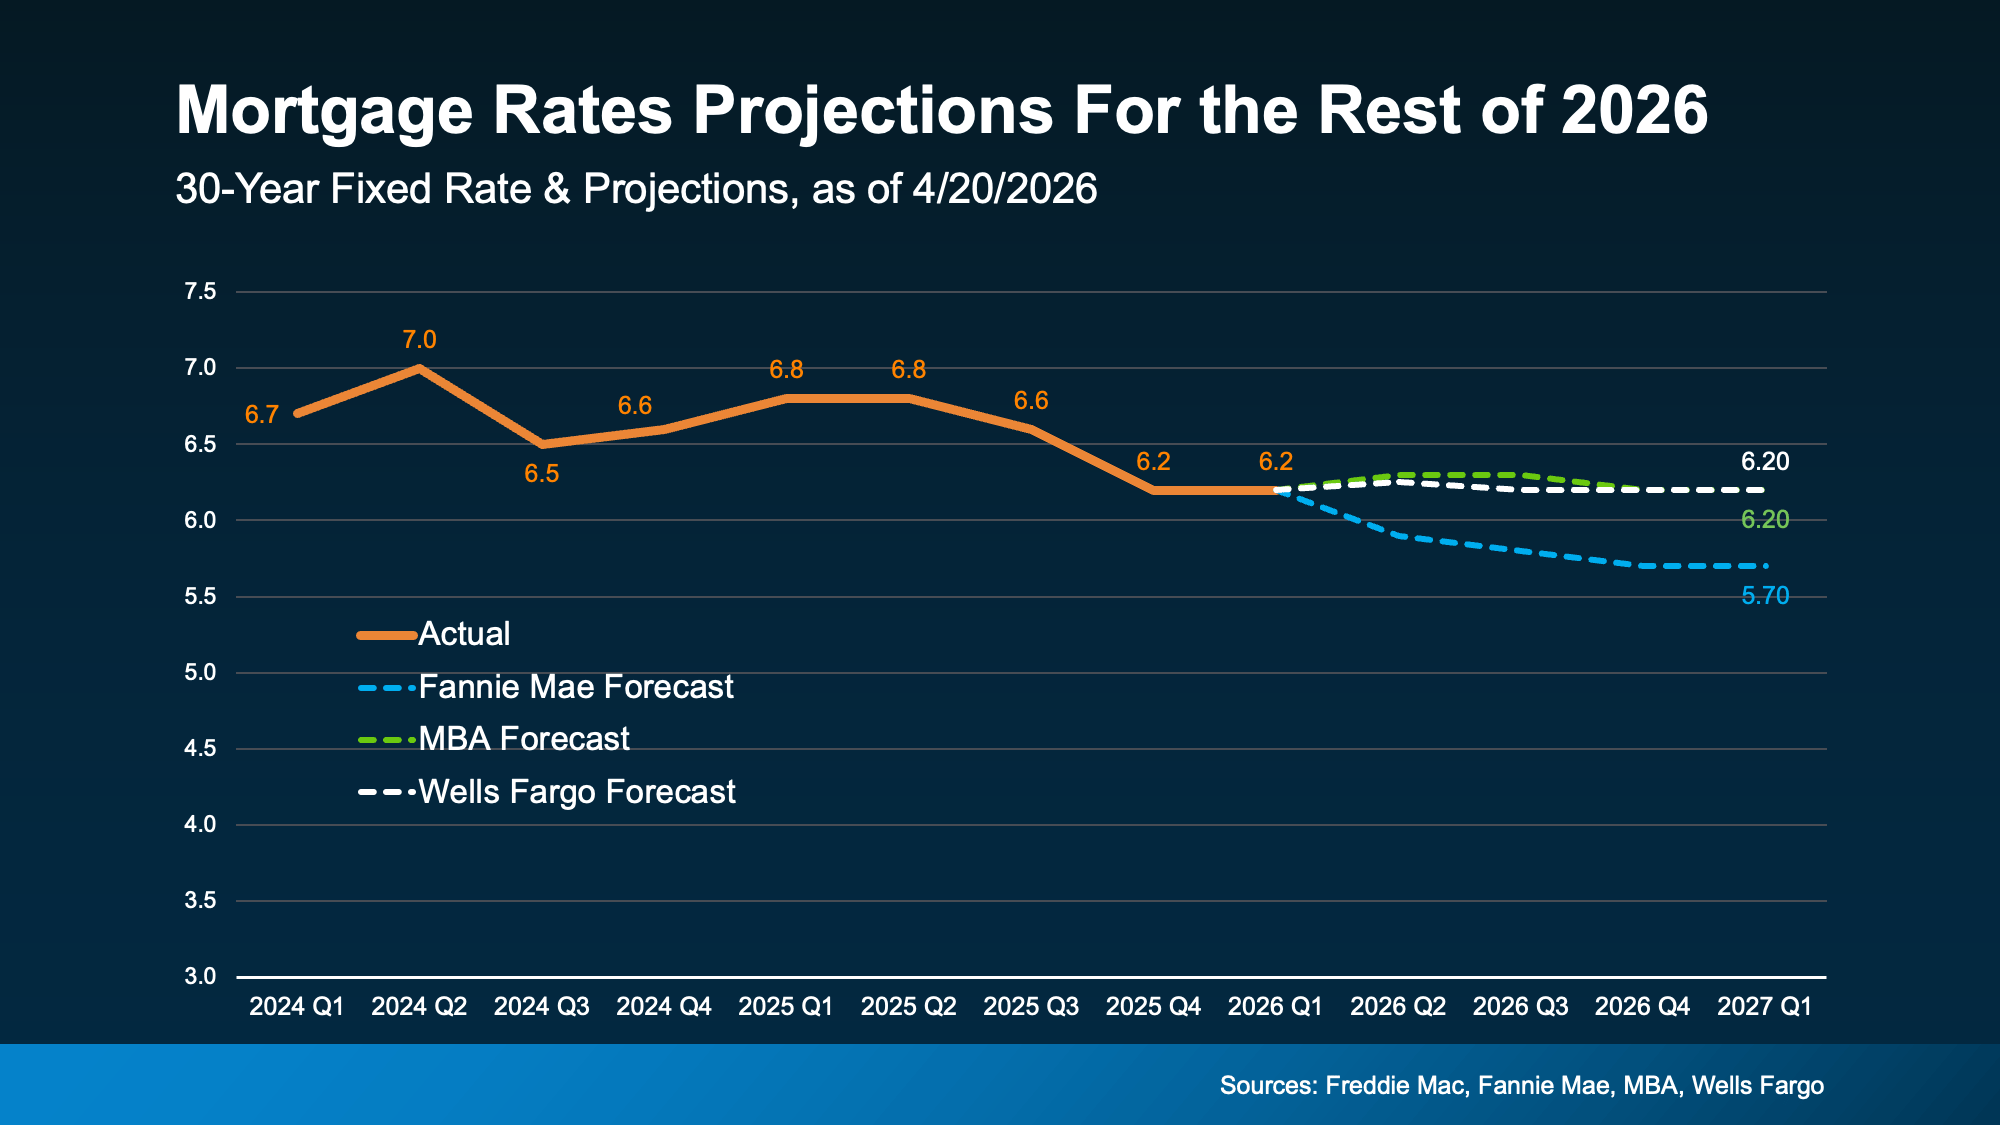 Of course, this depends on where inflation and the economy go from here. But, based on what we know today, waiting for a big drop in rates may not work out the way some people hope. As U.S. News explains:
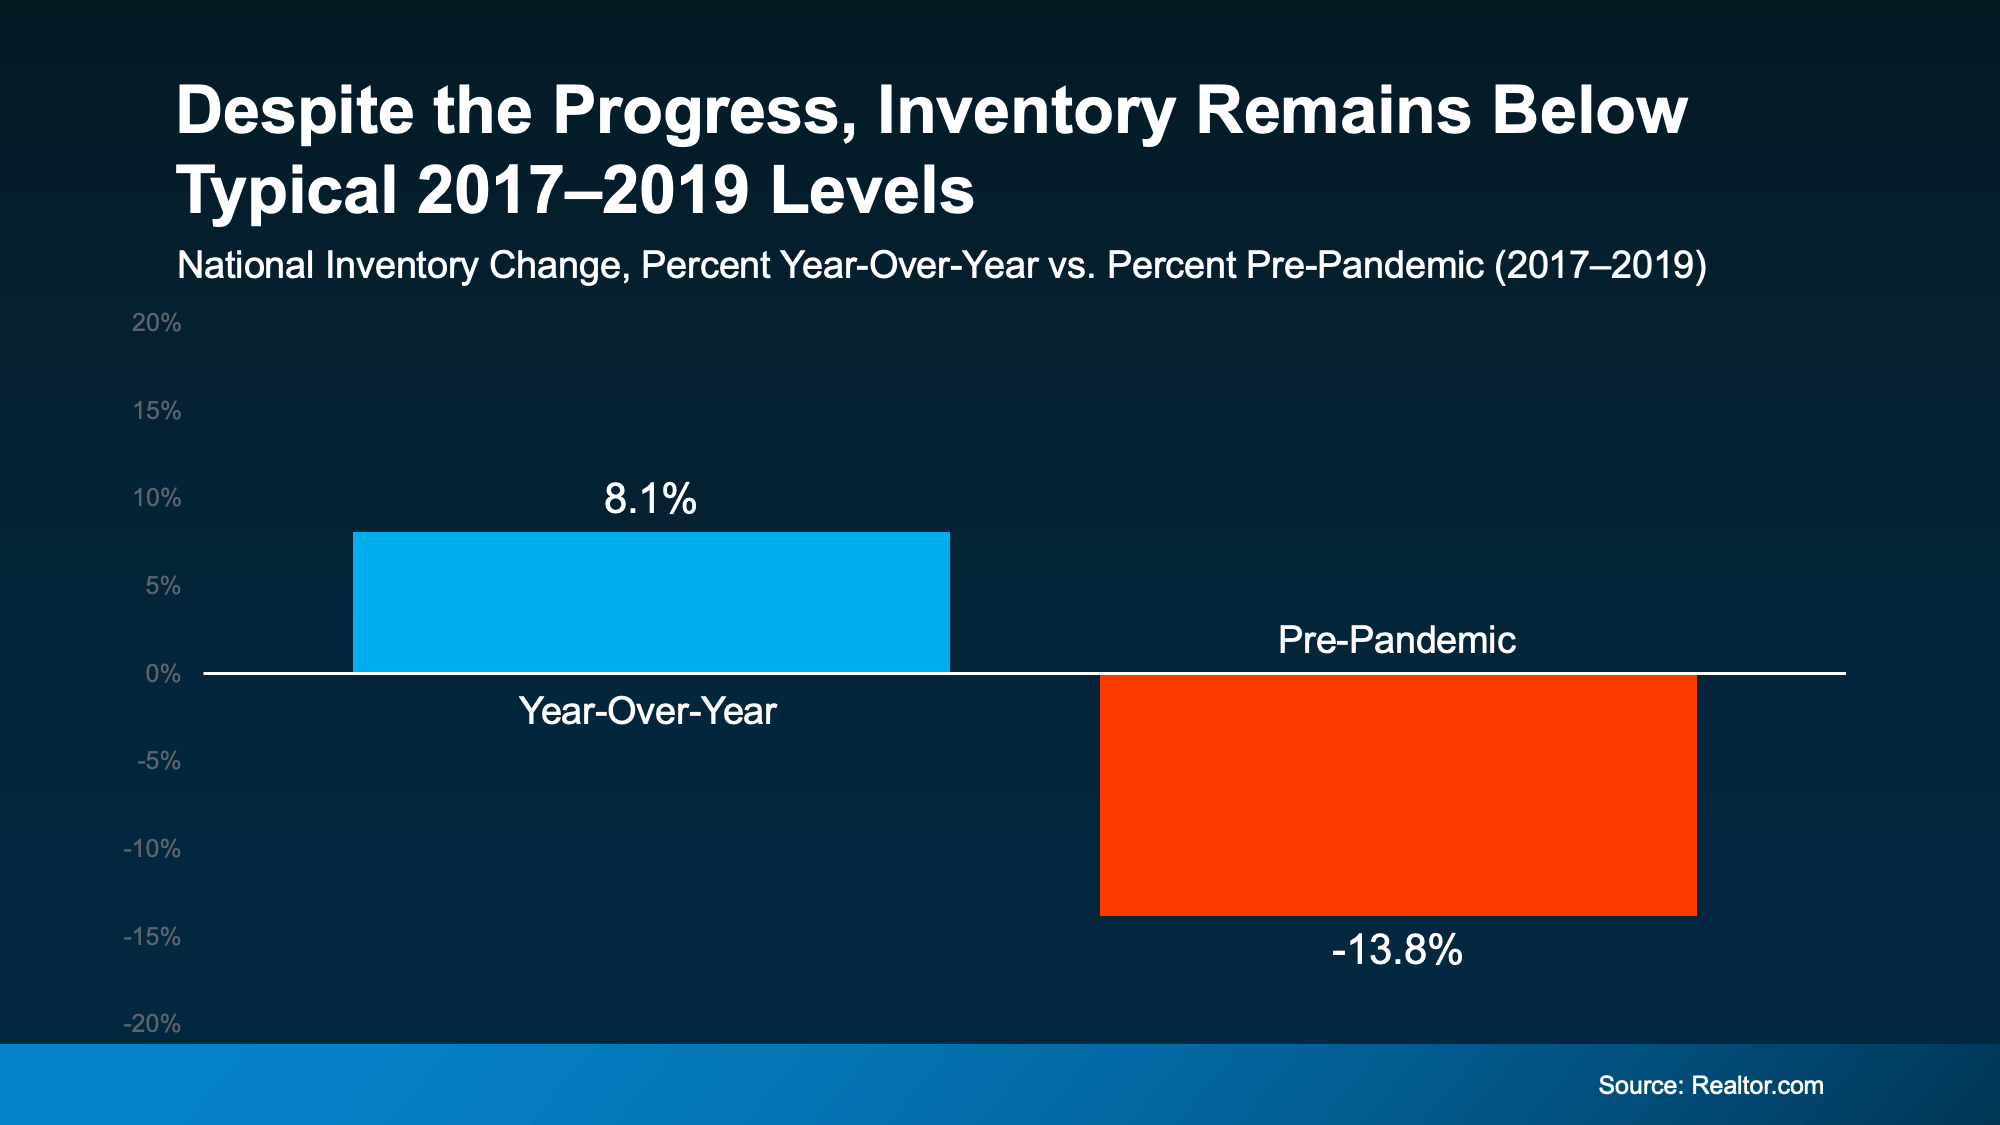 While it can vary a lot based on where you live, only
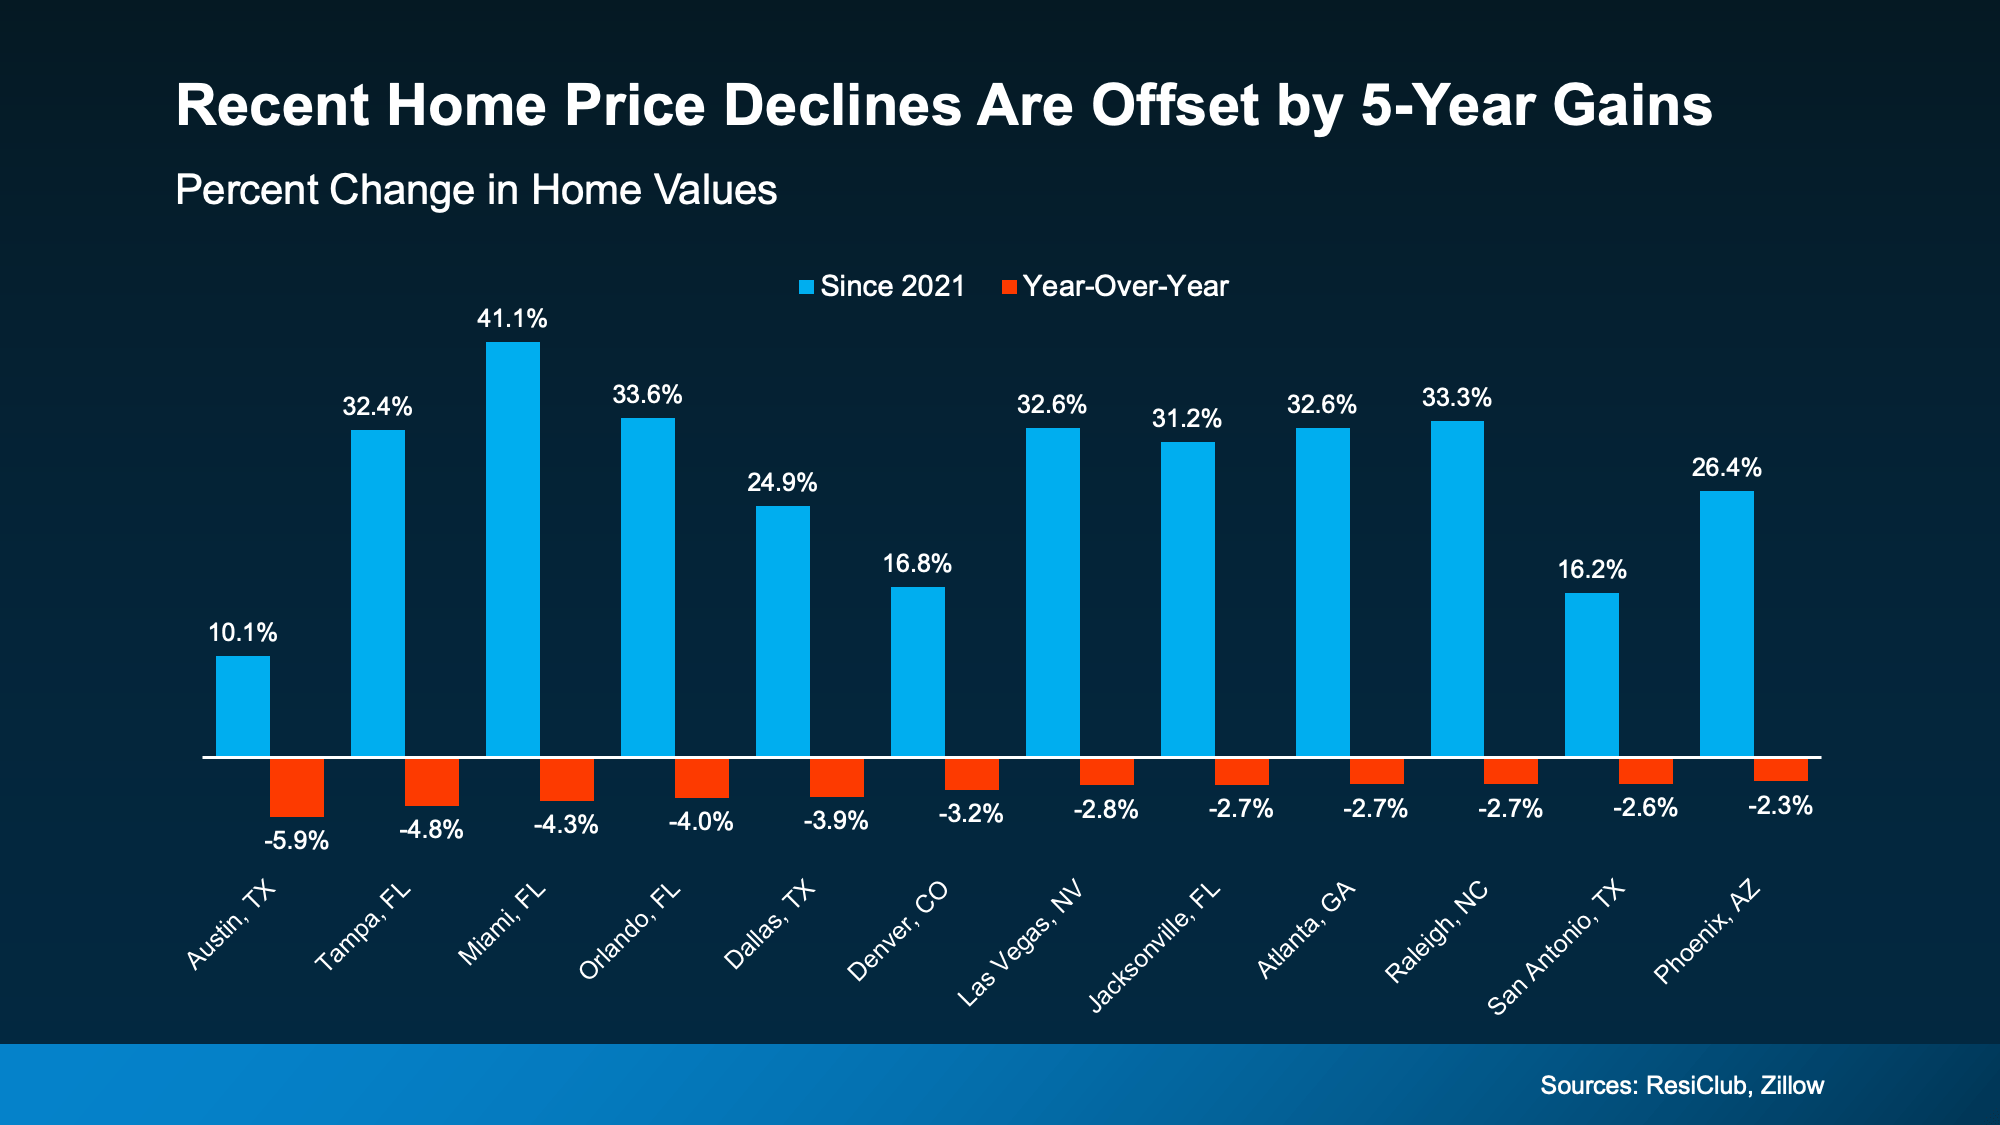 That’s not a crash. That’s just prices moderating after a few record-breaking years.
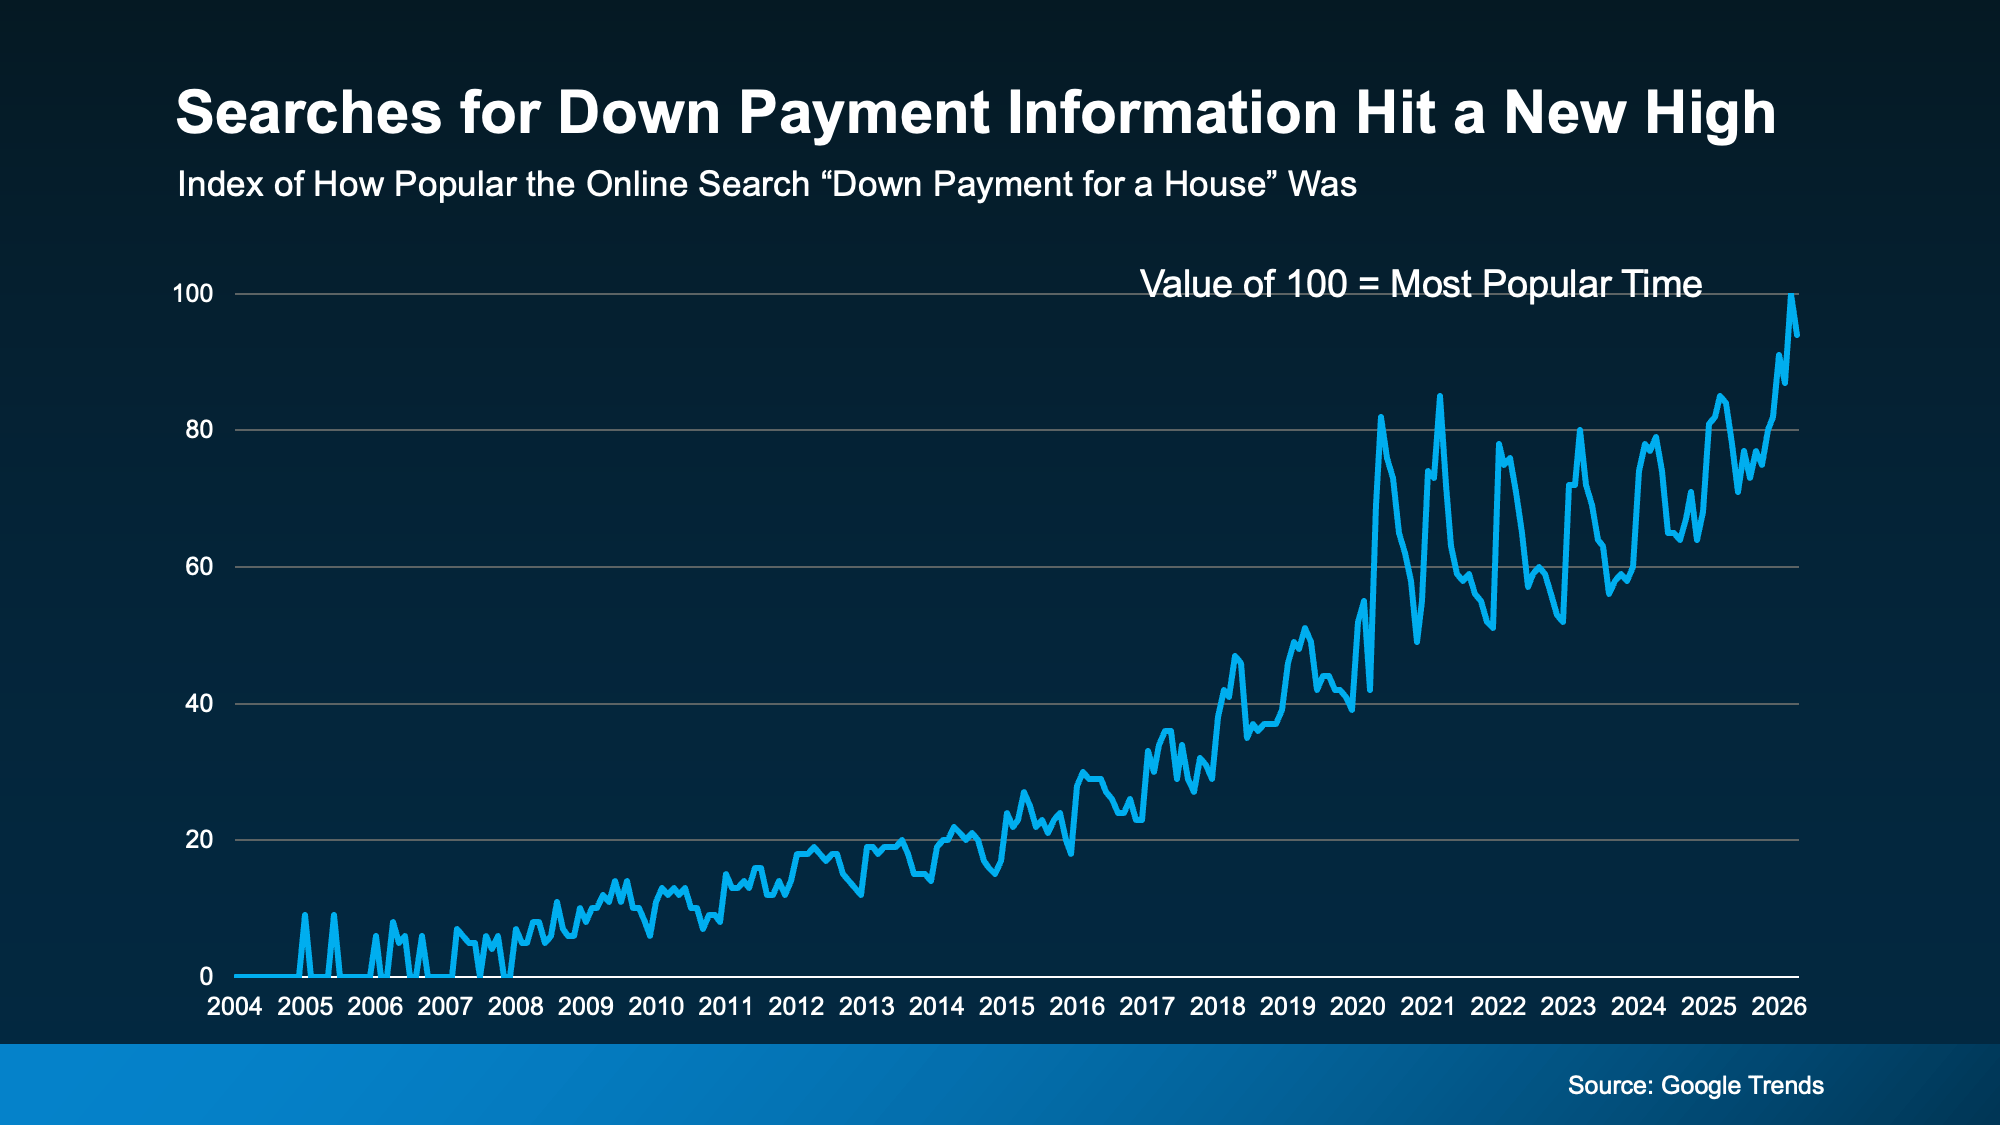 If you’re wondering the same thing, you can always turn to the internet for answers. But a lot of the time, it’s better to ask a local expert. Because here’s what a pro would tell you.
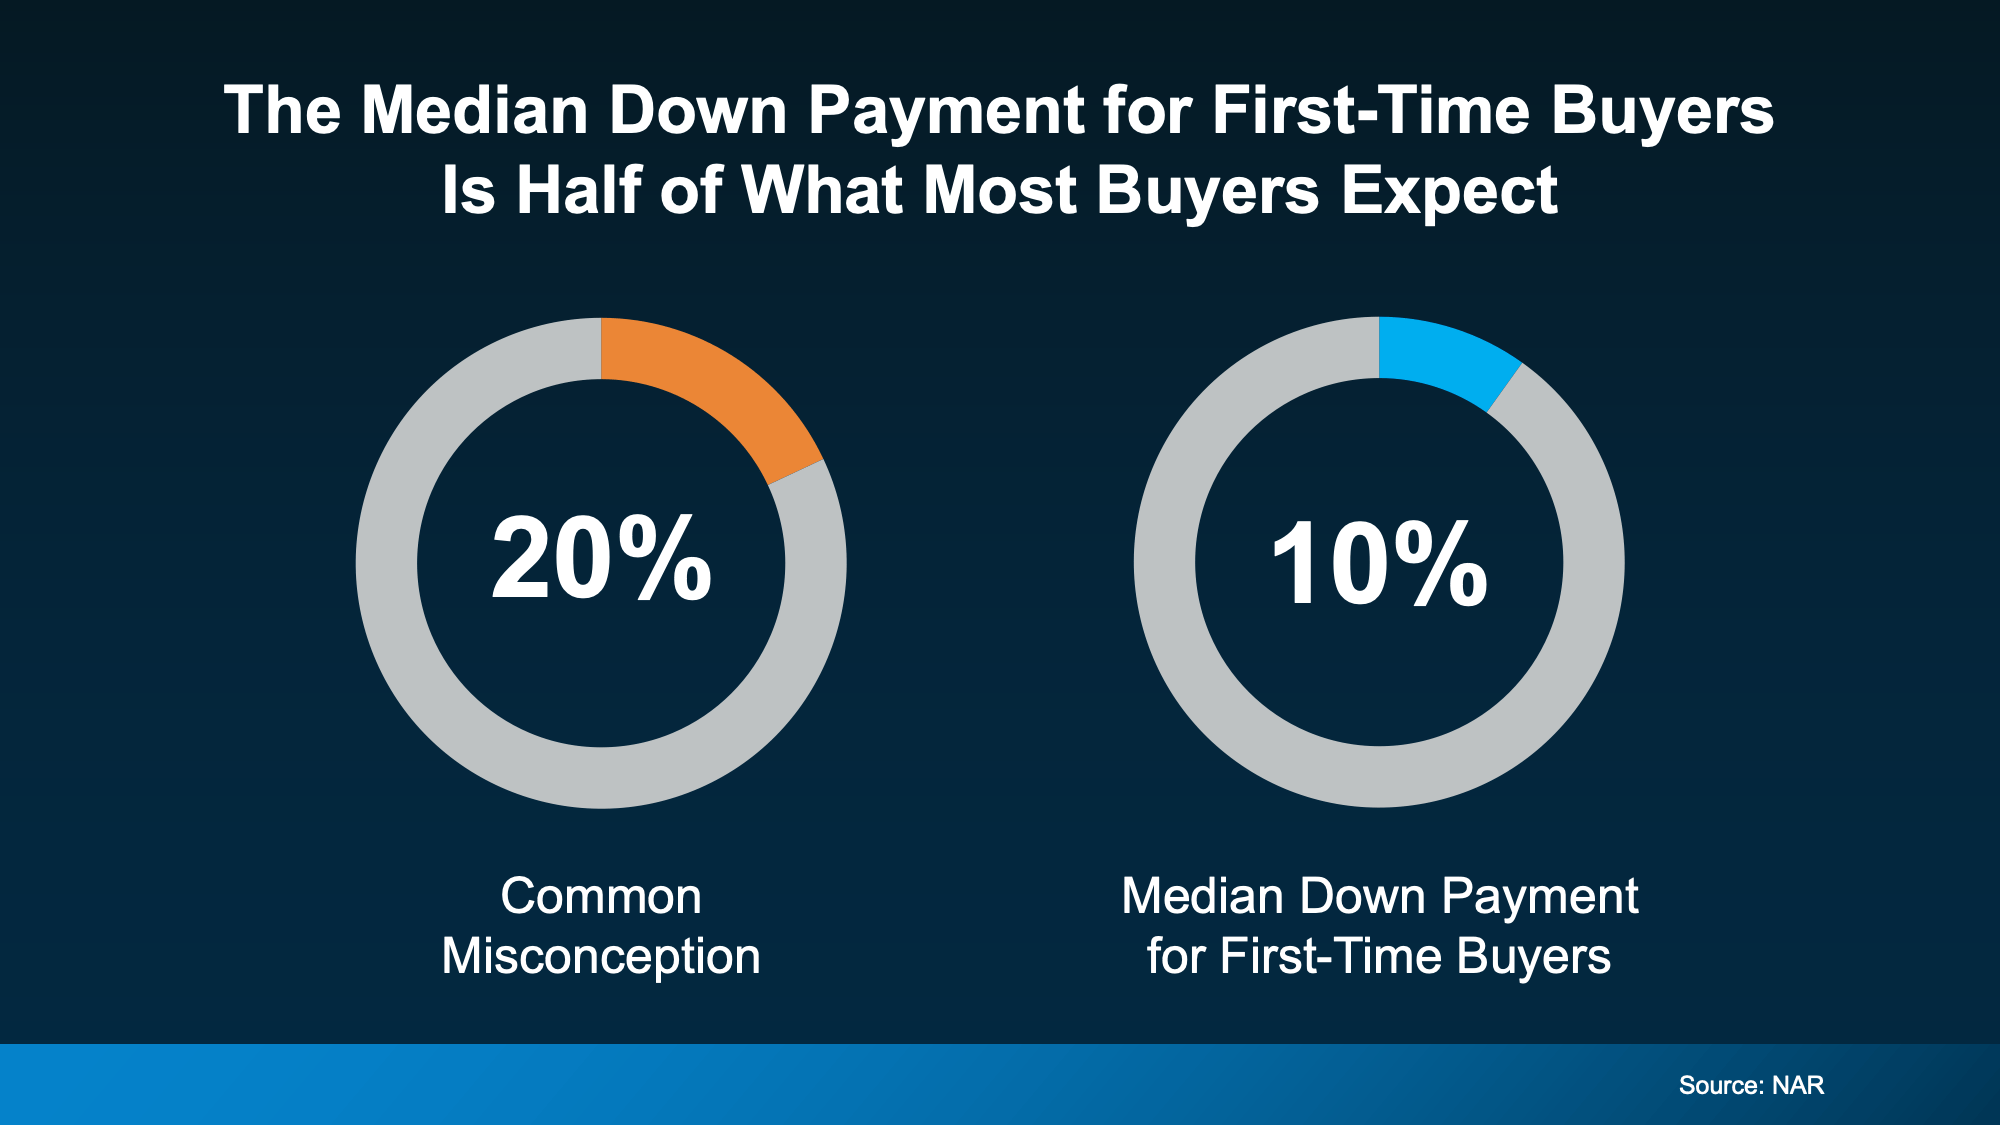 That means if you’re aiming to save 20% because you think you have to, you may be setting a timeline that’s longer than necessary.
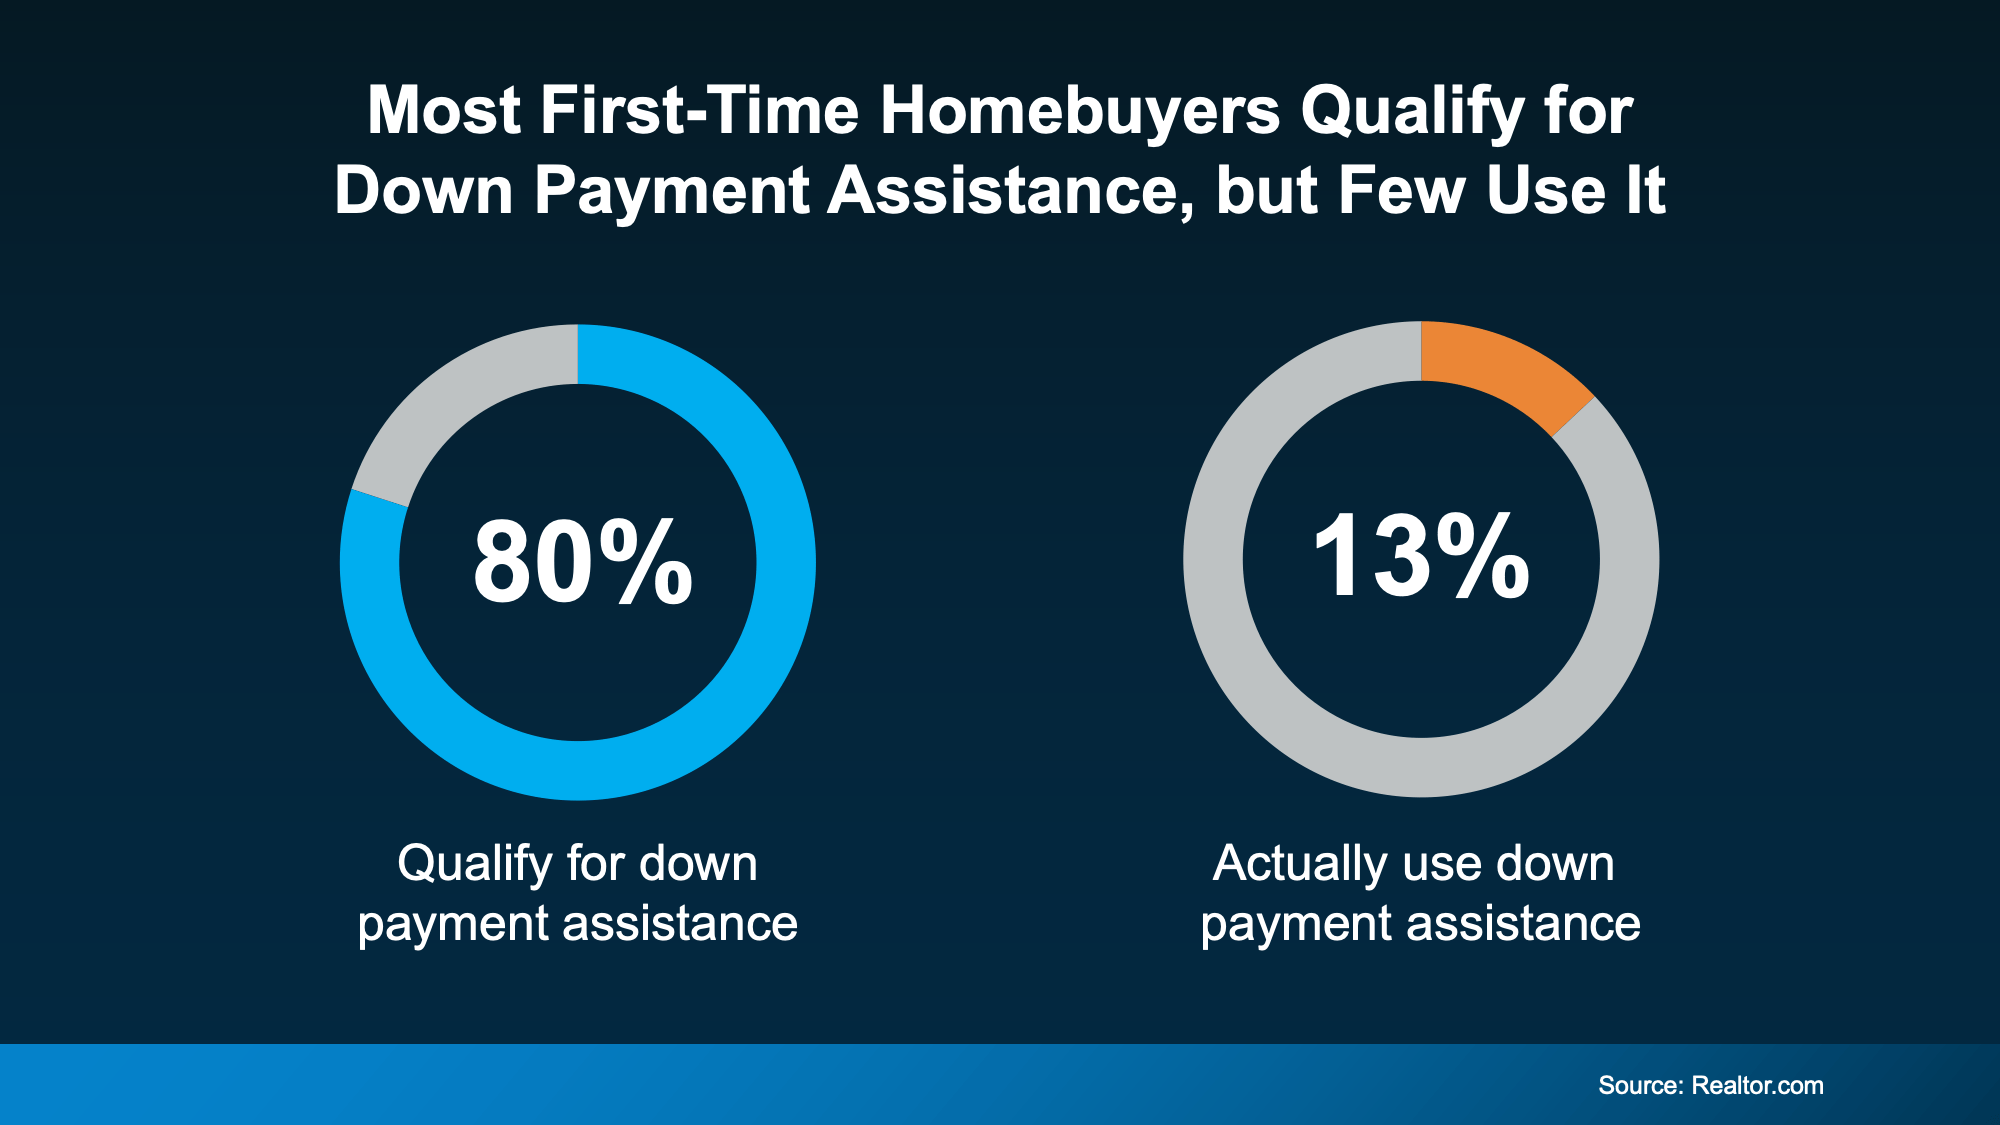 And that’s another big miss holding would-be buyers like you back.
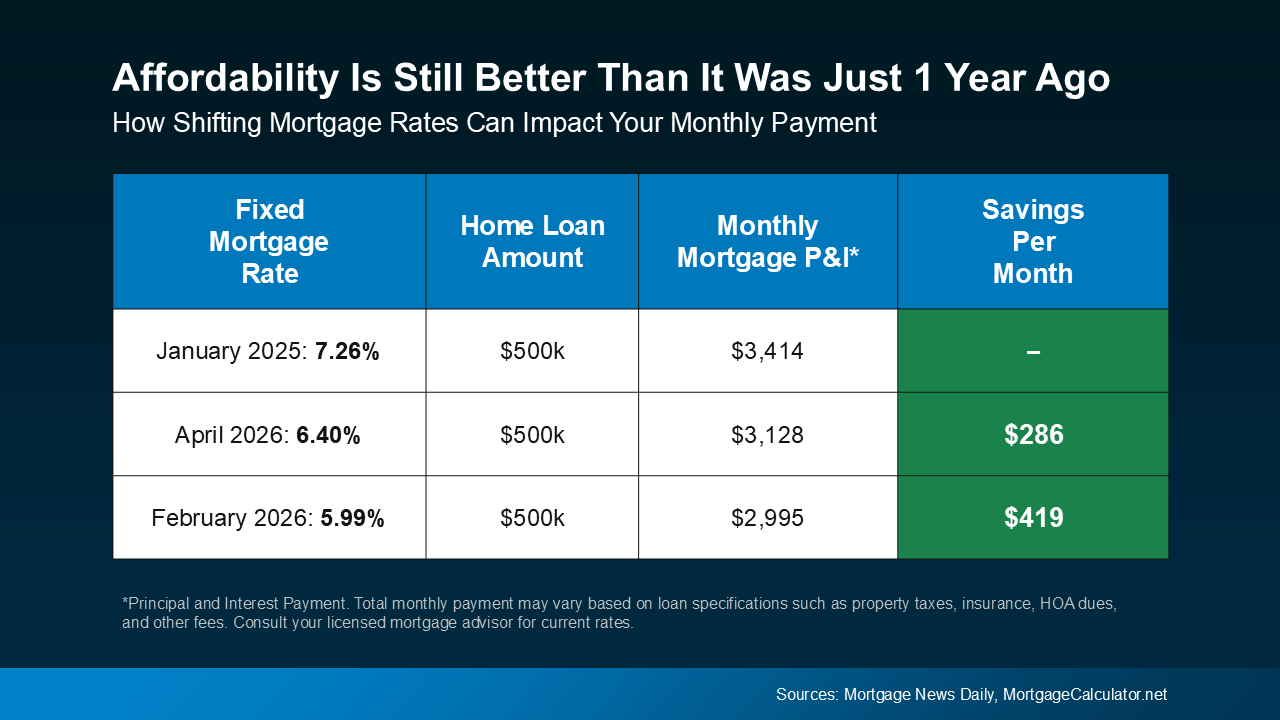 Sure, your monthly payment would’ve been a little less expensive a few weeks back. But hindsight is always 20/20.
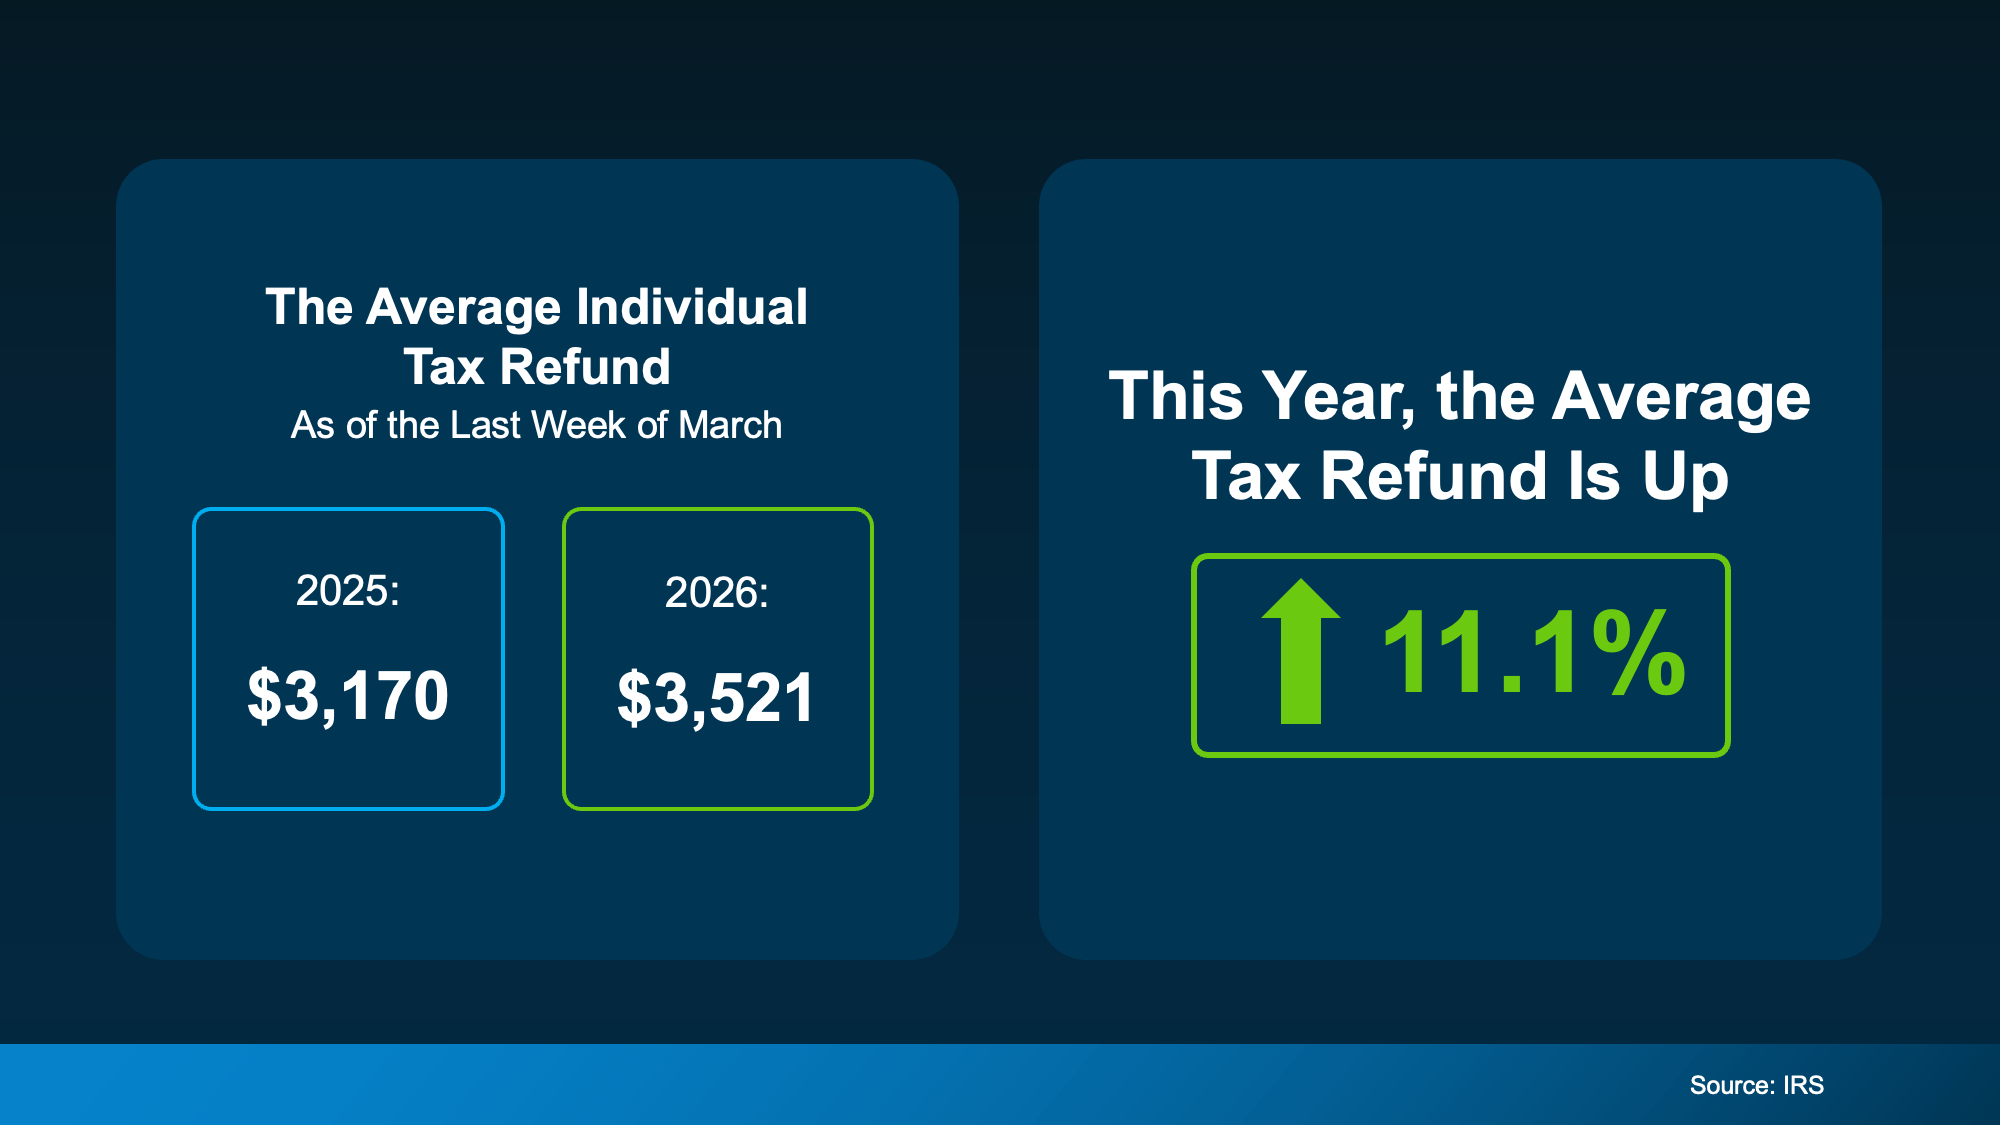 Of course, your exact refund will vary. But any extra money you get is a good thing, especially when affordability is still tight.
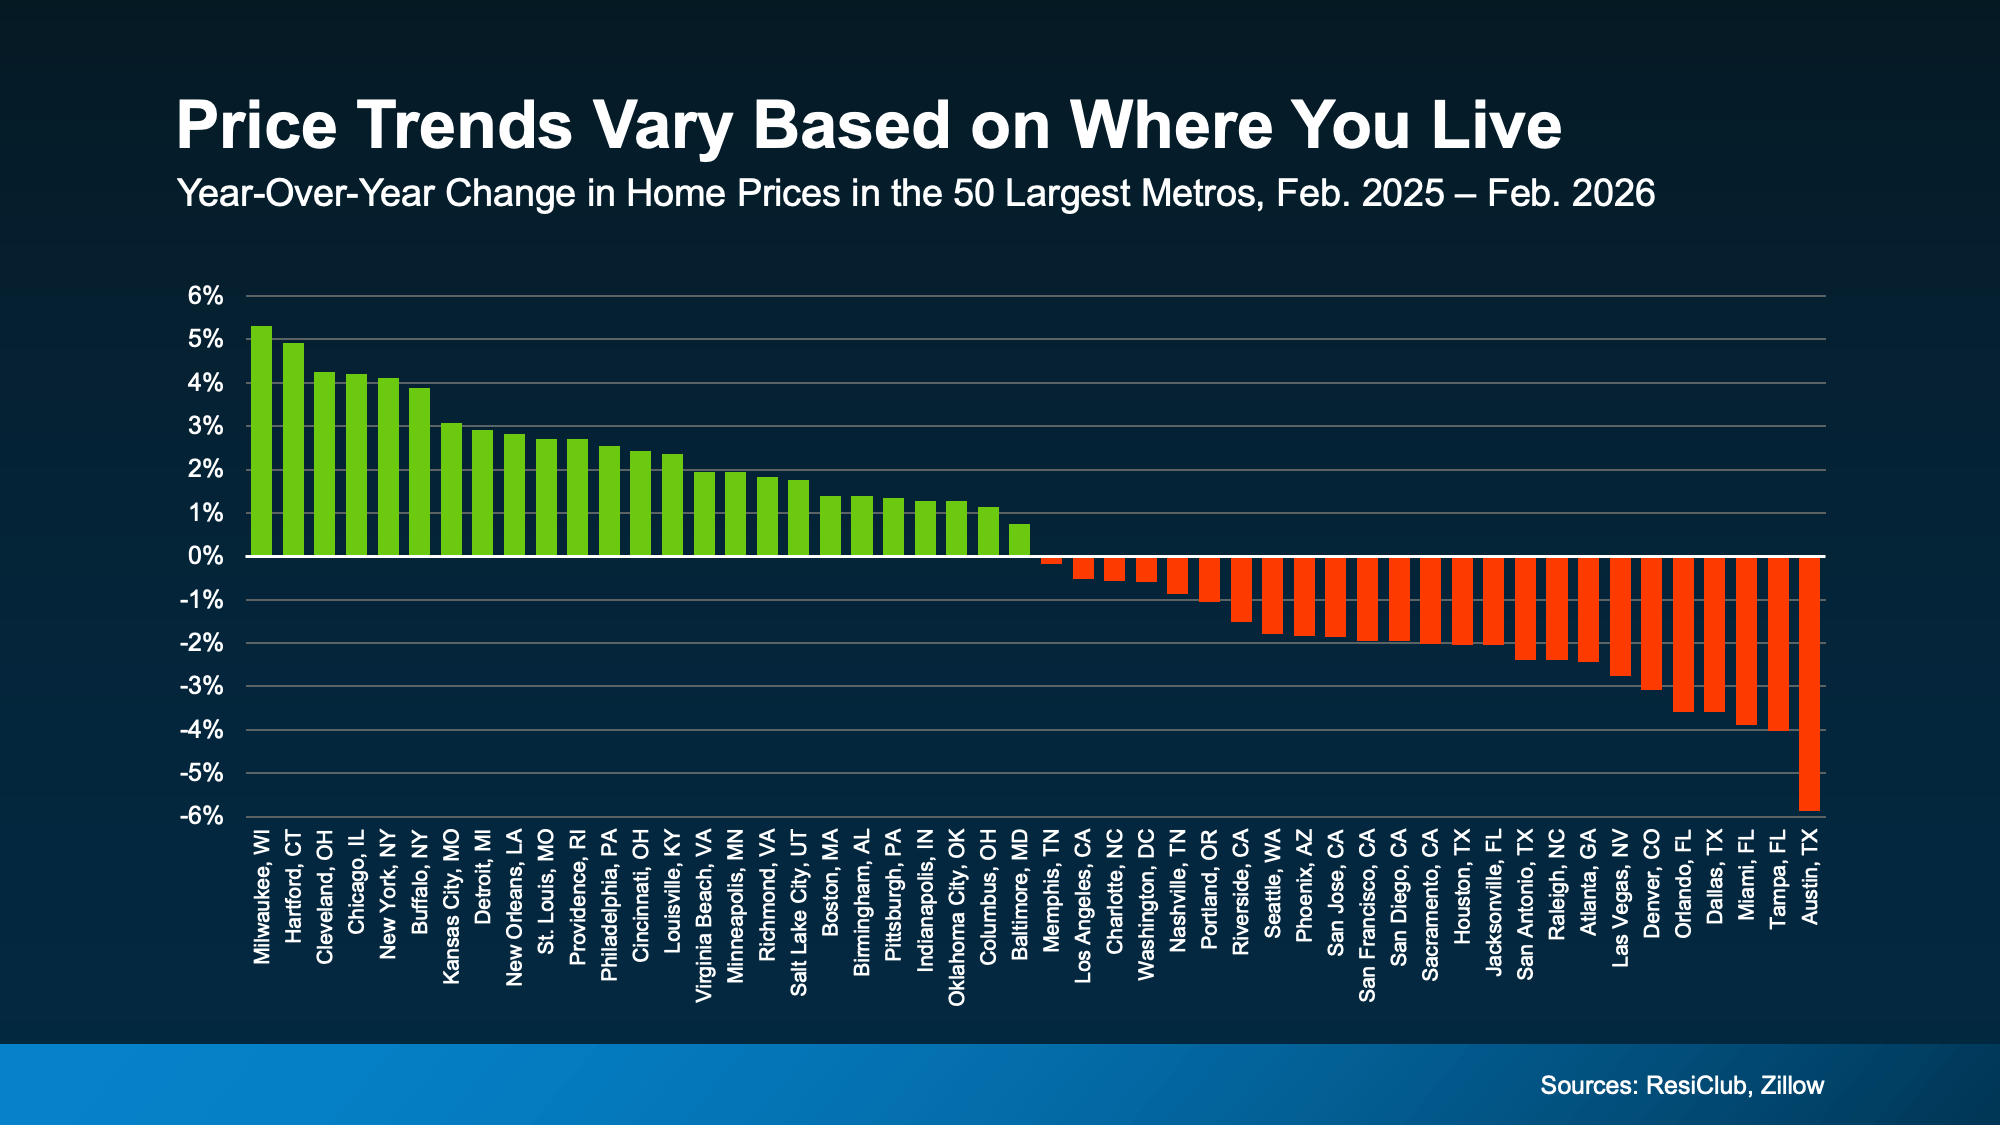 Unfortunately, the online chatter only focuses on the markets where prices are down – and that makes it sound like something bigger is happening.
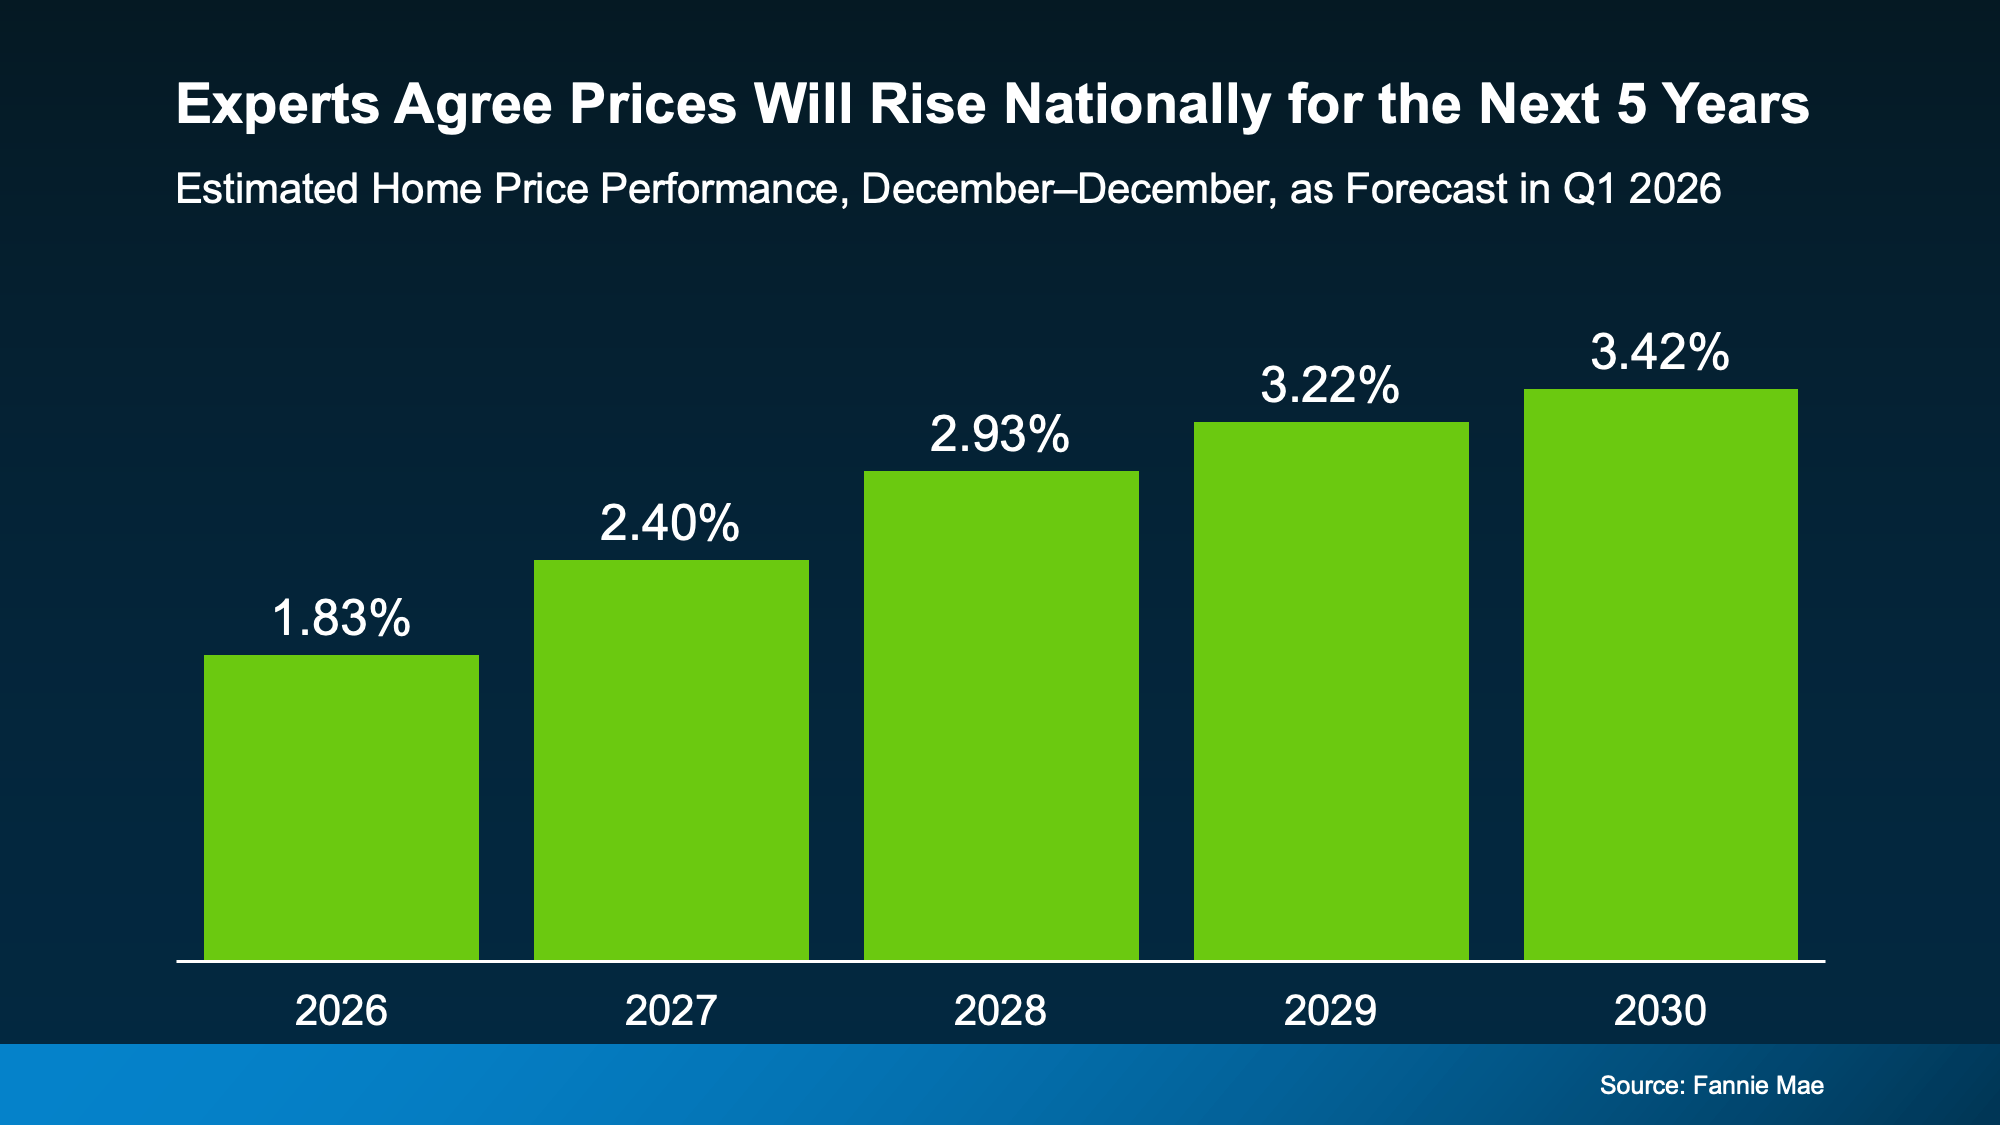 That rise will be moderate, particularly this year, but the trend is clear. Nationally, prices are forecast to grow every year now through at least 2030 – and that’s normal. Daryl Fairweather, Chief Economist, at Redfin explains:
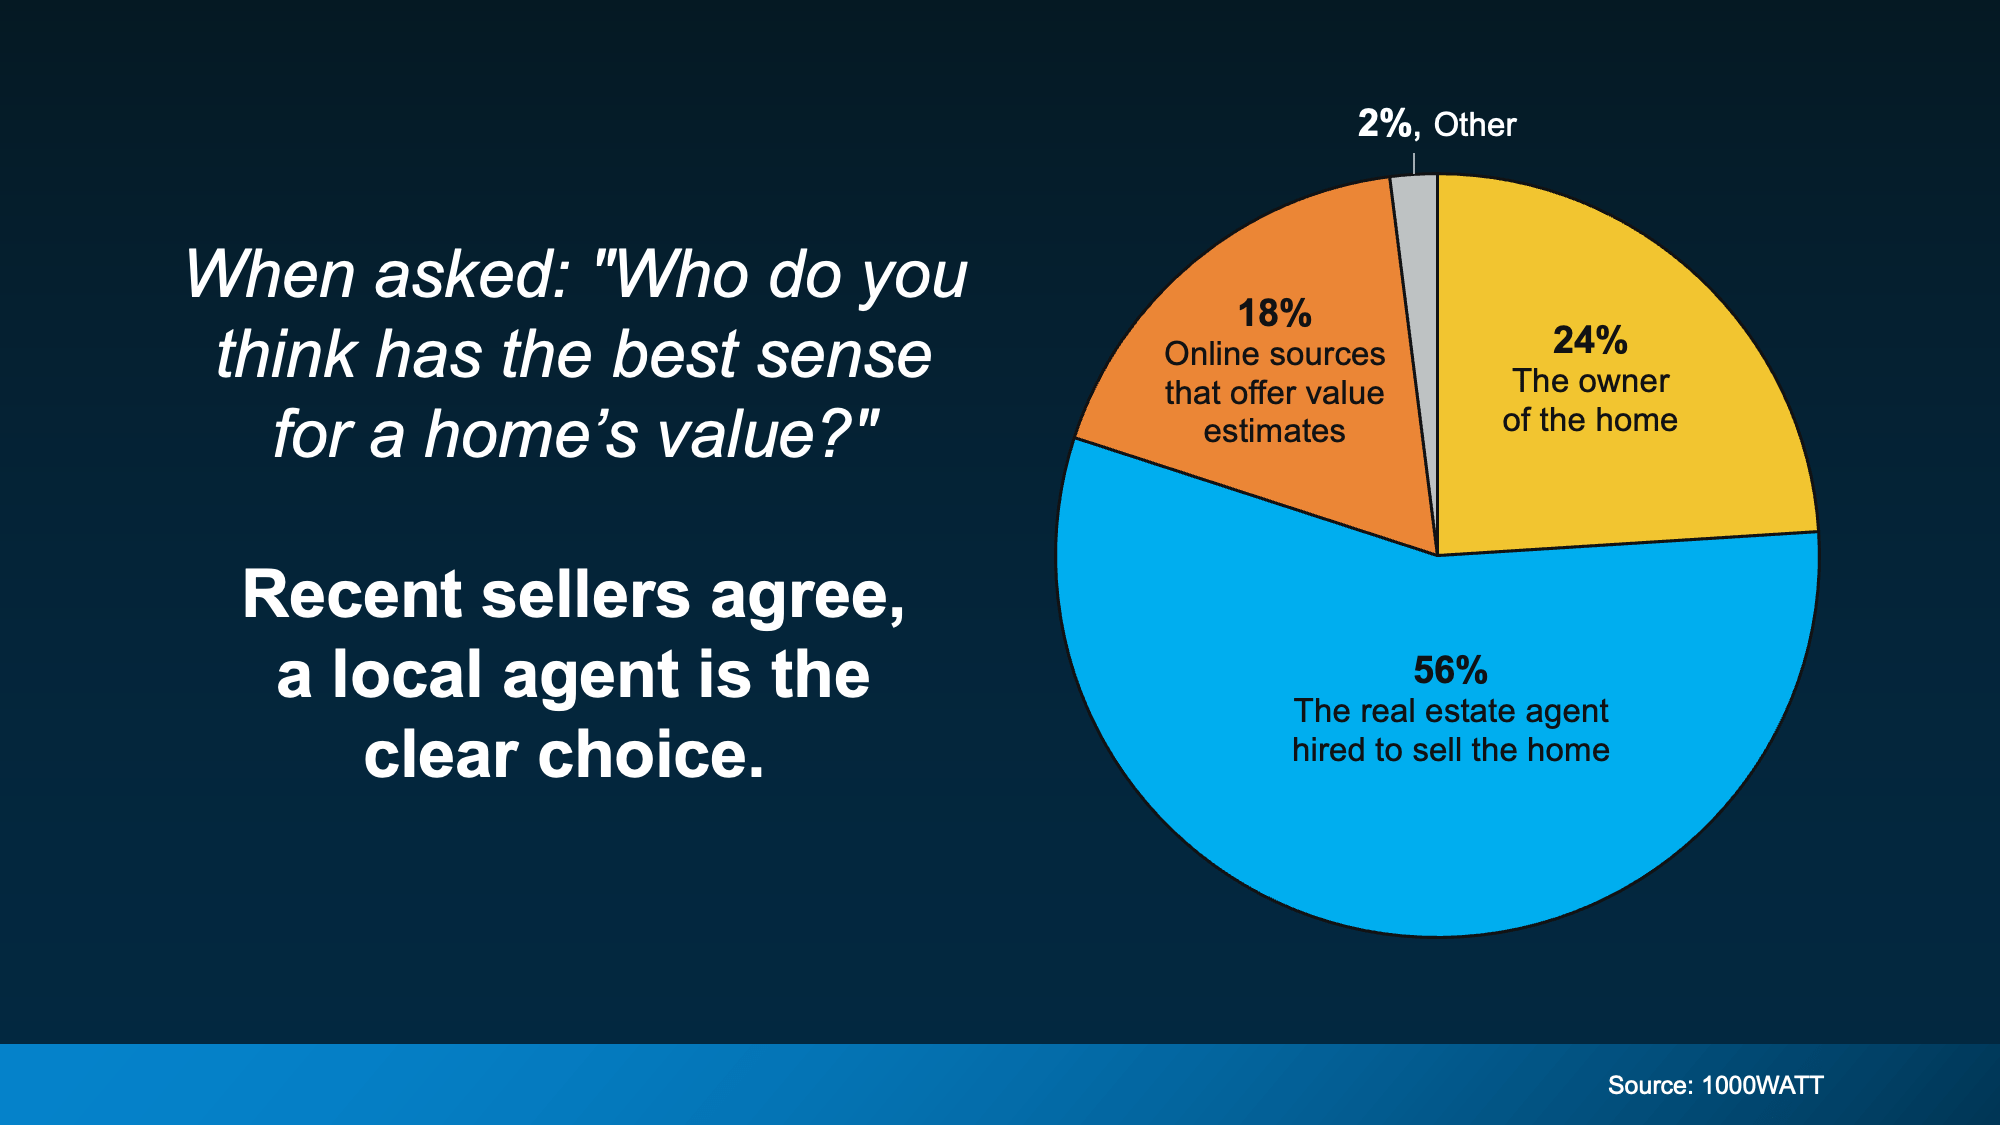 That confidence isn’t accidental. As Bankrate puts it:
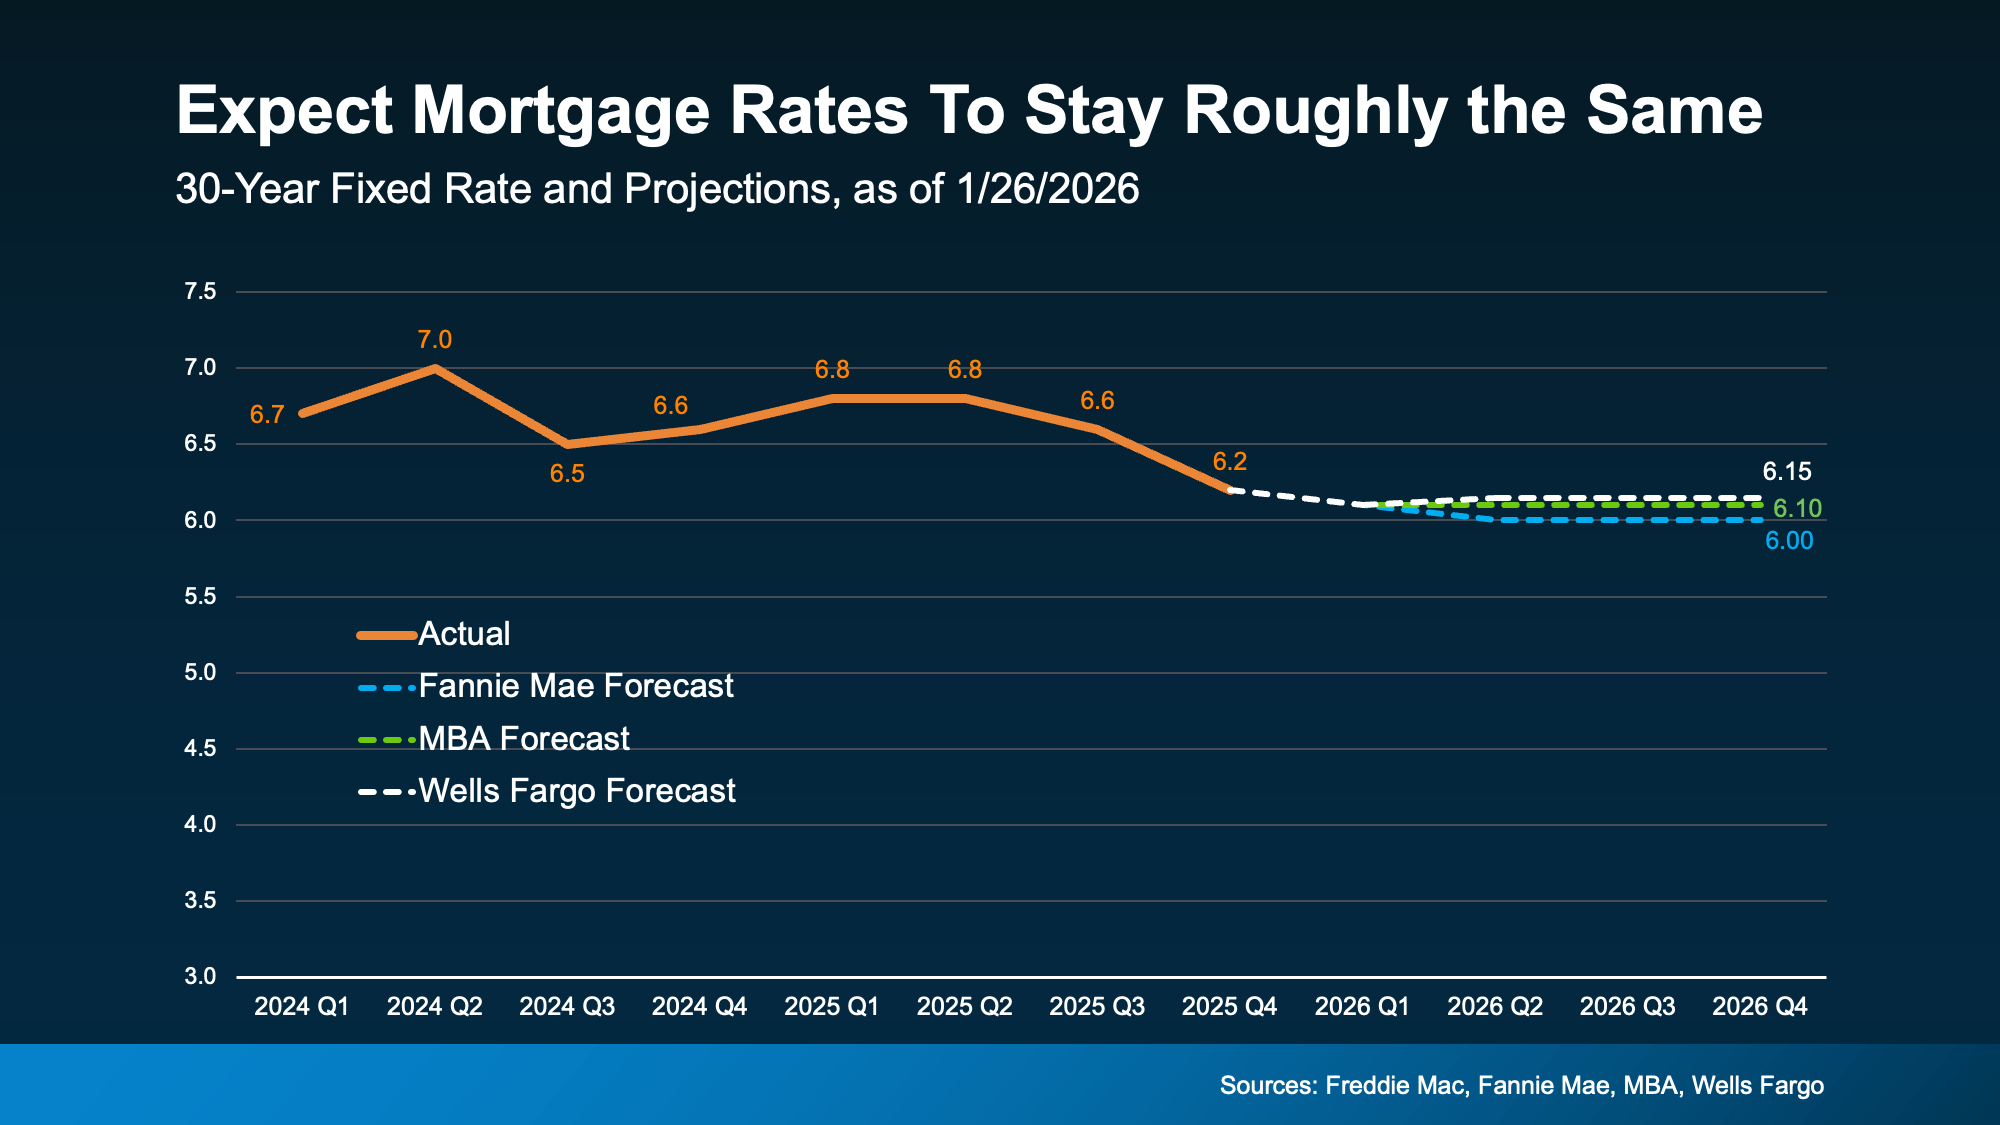 That's not a bad thing, especially if you consider how much rates have already come down. Over the past 12 months, they’ve dropped roughly a full percentage point. And for many buyers, that means affordability has already improved more than they may realize.
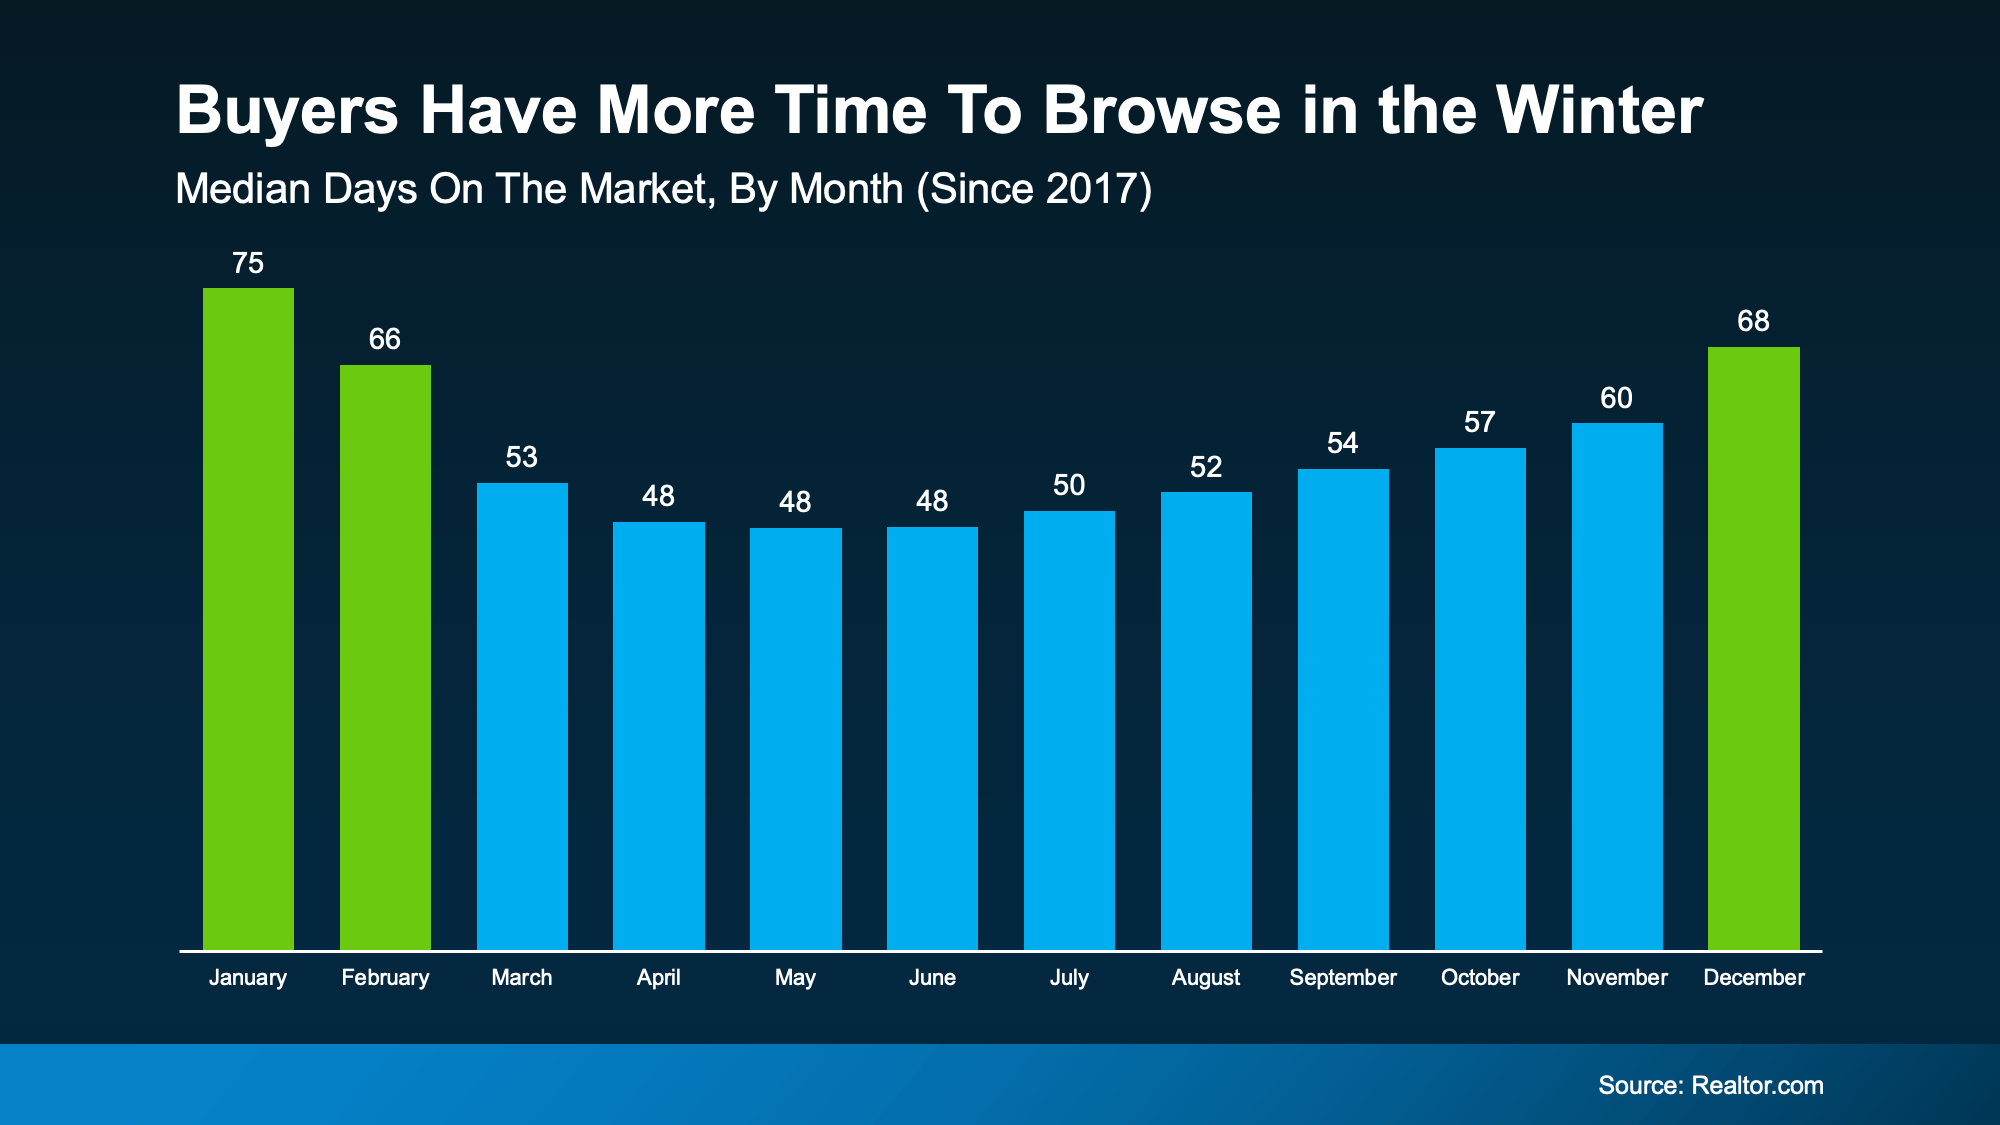 Homes sell faster in the spring, and slower in the winter. And that can be a worthwhile perk for buyers who want to get ahead before their decisions start to feel rushed.
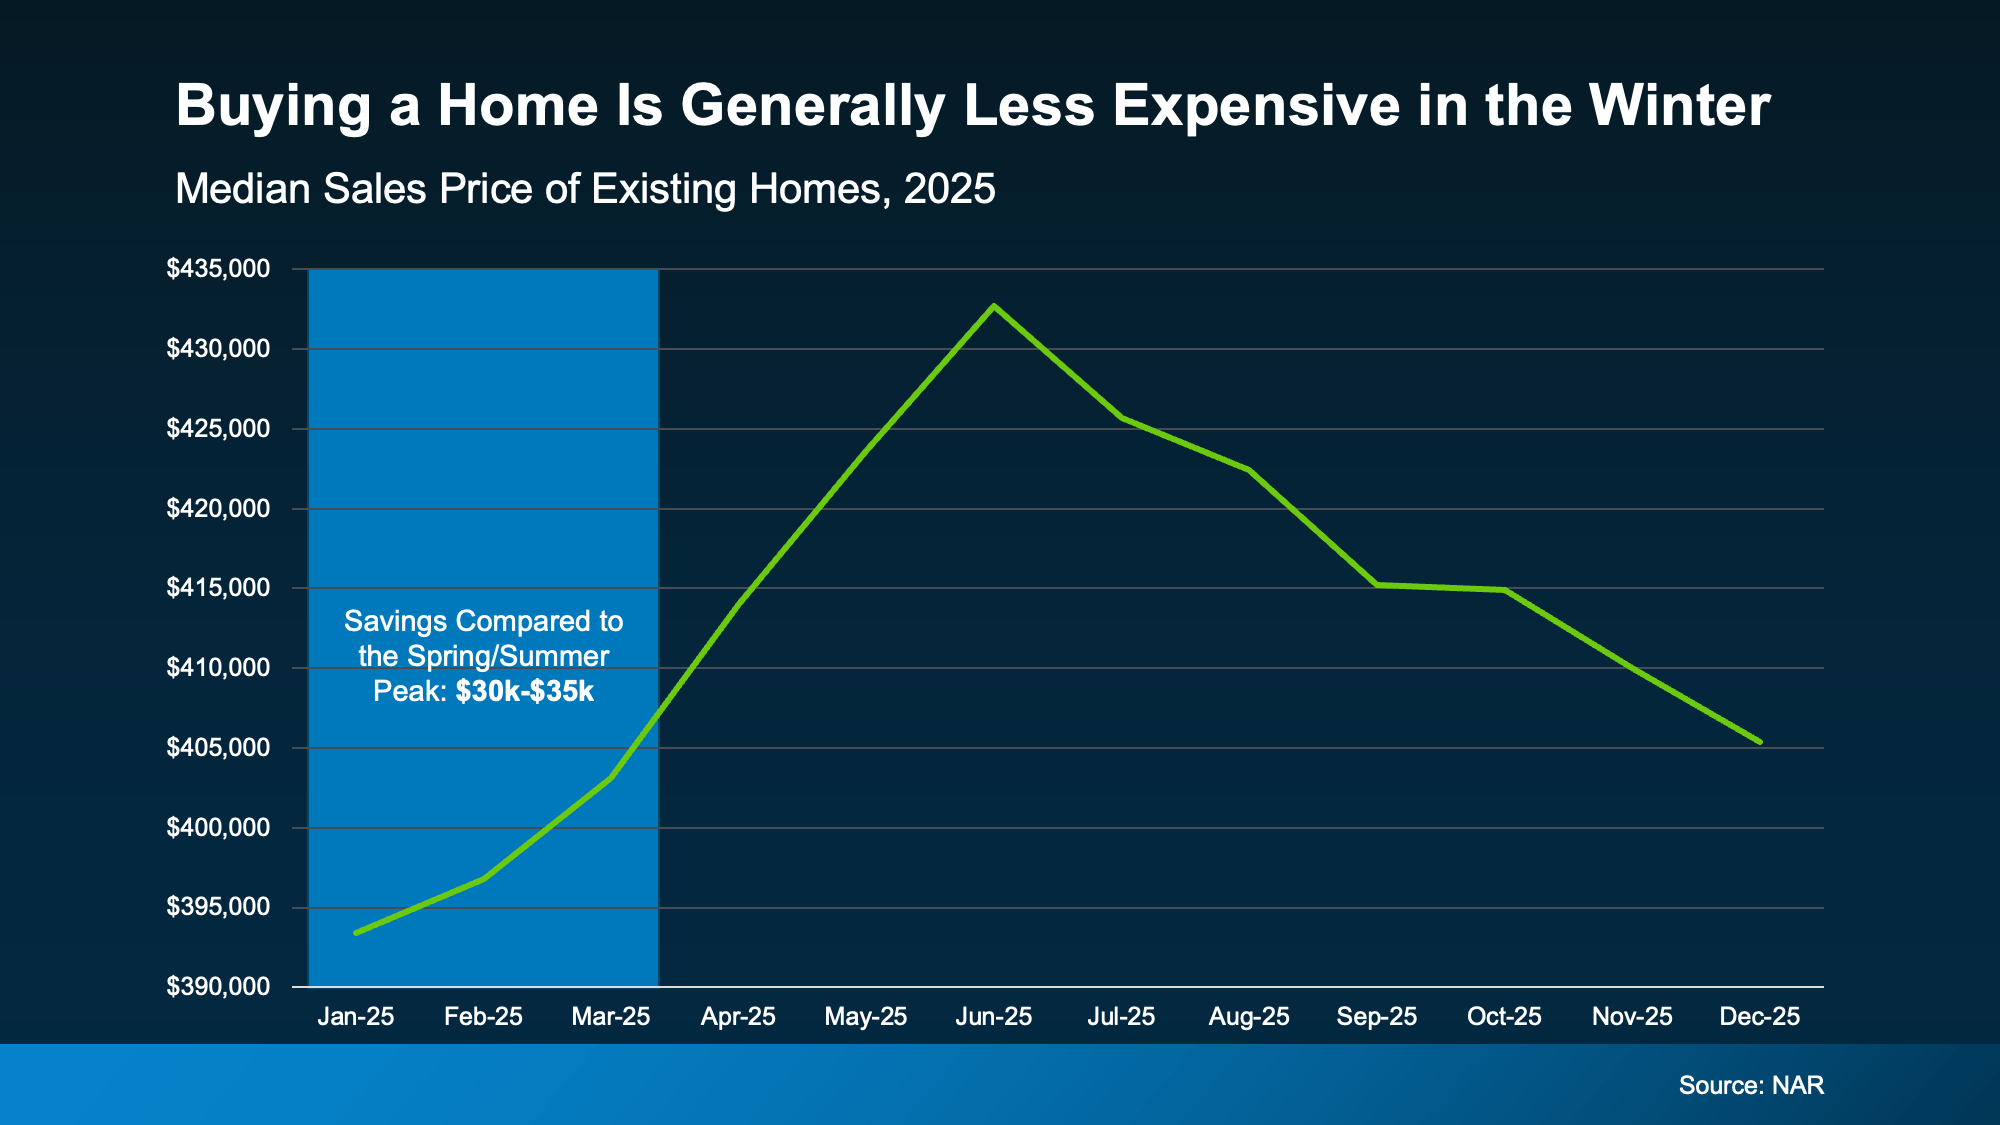 And let’s be honest, for a lot of buyers today, every little bit of savings helps. That’s why buying just a few weeks earlier, before prices ramp up, will be better for you and your wallet.